
For Insurance & Public Adjusters
A General Contractor
Who Understands
the Claim.
We've been on both sides of an insurance claim. That makes us a different kind of contractor — one who documents thoroughly, scopes completely, and communicates in a way that keeps your file moving.
Why We're Different
We've sat on your client's side of the table.
In October 2017, the Tubbs Fire destroyed Kelly's family home in Fountaingrove. She evacuated with almost nothing, filed a total-loss claim, and spent the next two years learning everything there is to know about insurance reconstruction — not as a professional, but as a homeowner trying to get her family's house rebuilt.
She learned where claims fall short. How supplemental claims actually work. What gets overlooked in initial assessments. And what it takes to get a settlement that covers what needs to be rebuilt. She also learned that the general contractor a homeowner chooses makes an enormous difference in whether the process goes smoothly or falls apart.
That experience is why Sonoma Residential Services approaches every insurance restoration project differently. We don't show up, do minimal documentation, and hope the claim holds. We do the work — thorough, detailed, and in a format that supports the file you're building for your client.
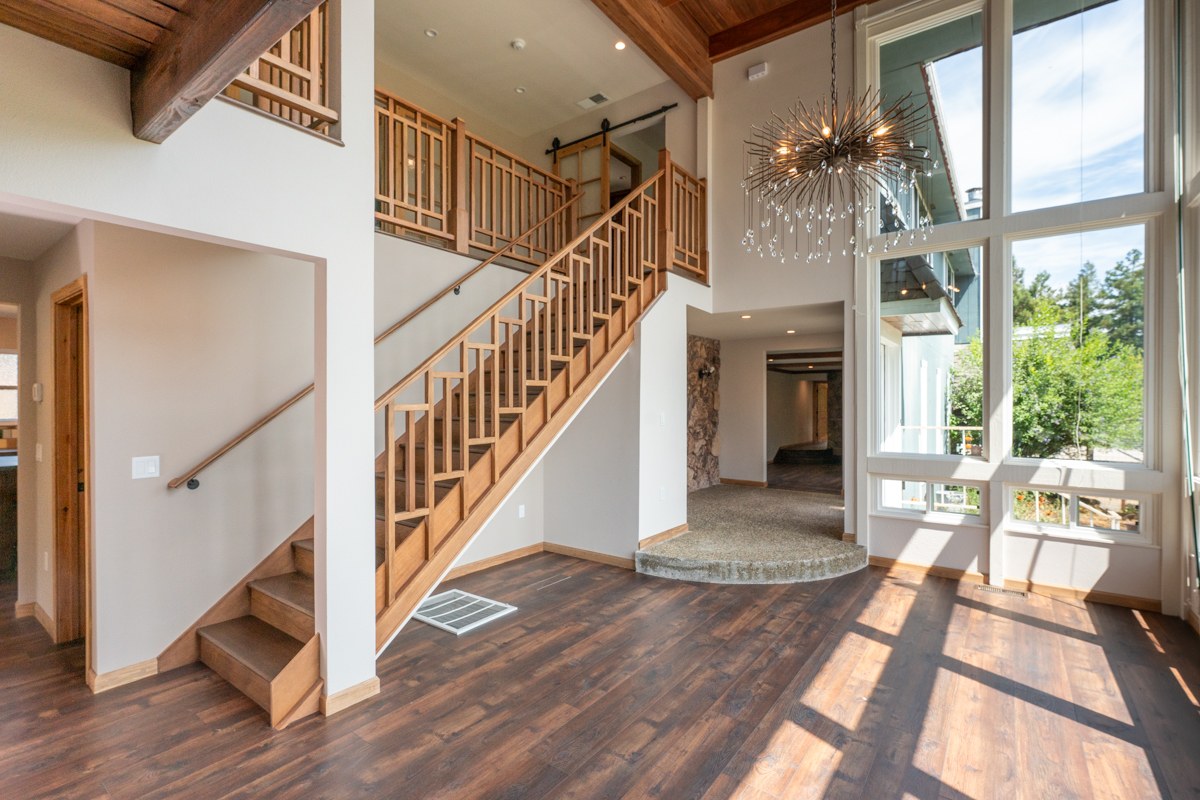
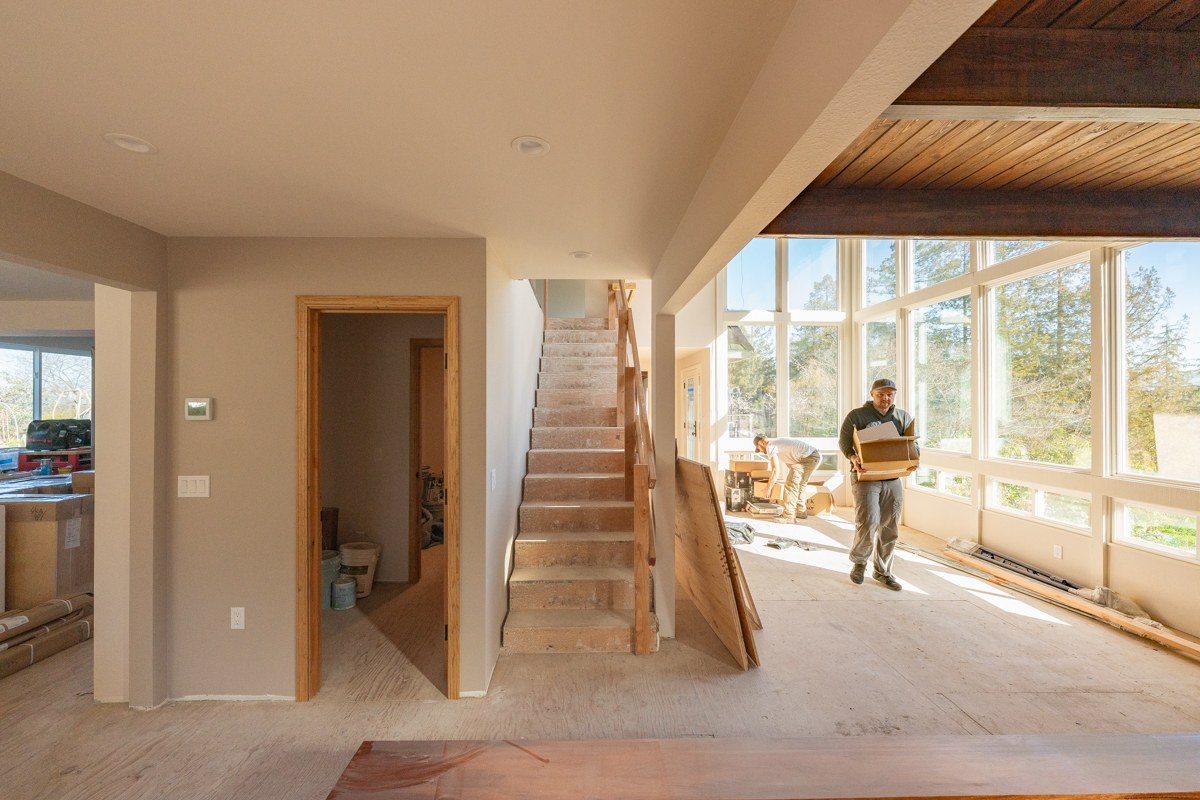
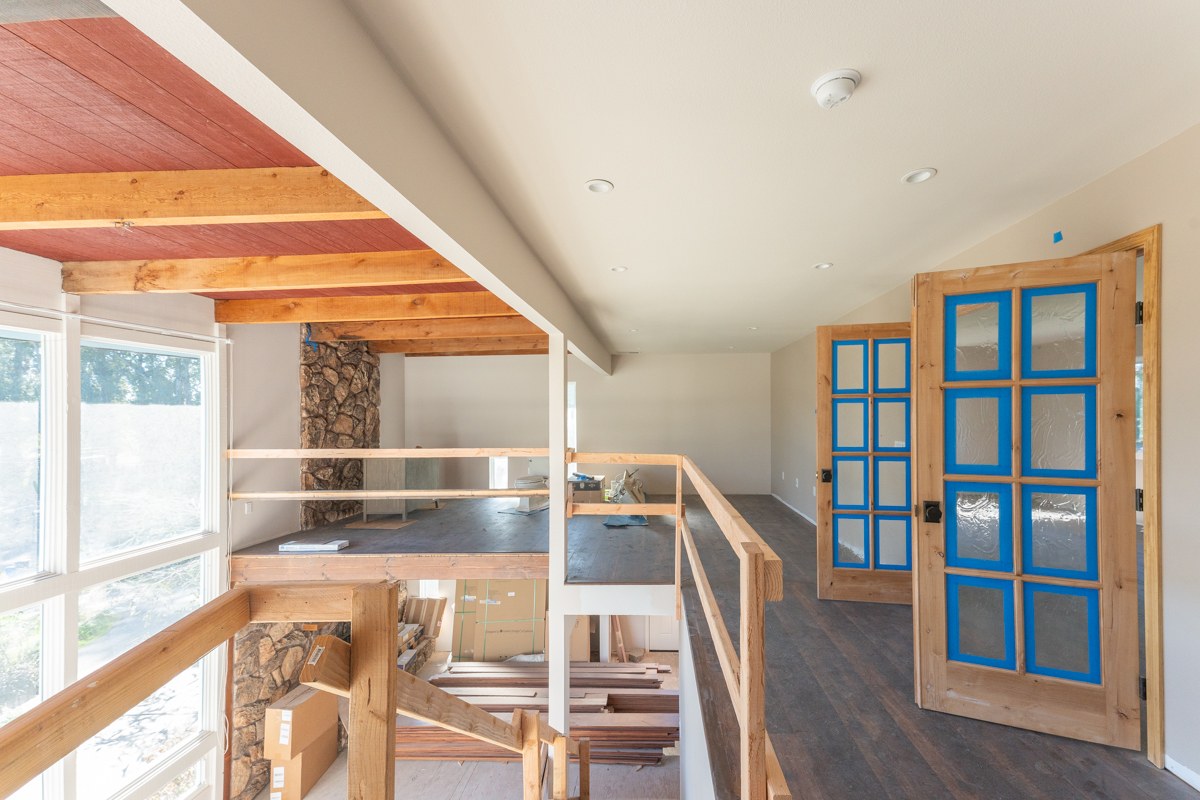
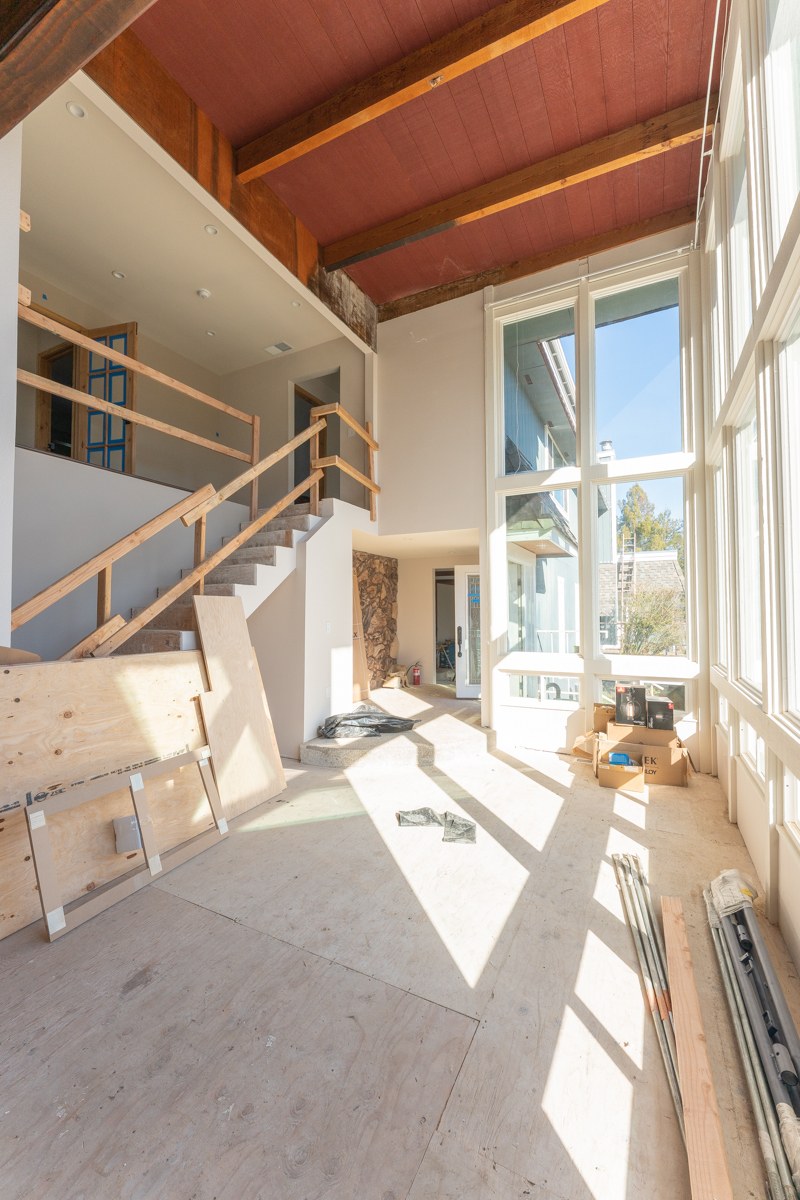
Total-Loss Fire Rebuild
Poplar Drive
Santa Rosa, Sonoma County
Total loss to reimagined home — with the documentation trail to back every line item.
Owner lost the home in the Tubbs Fire. We were brought in for the full rebuild — foundation through final walk. Every phase photographed and documented for the claim file. Reimagined floor plan within the claim envelope. The kind of project that proves the adjuster's confidence in the GC was earned.
Project Type
Fire Rebuild
Scope
Foundation to Finish
Claim
Total Loss

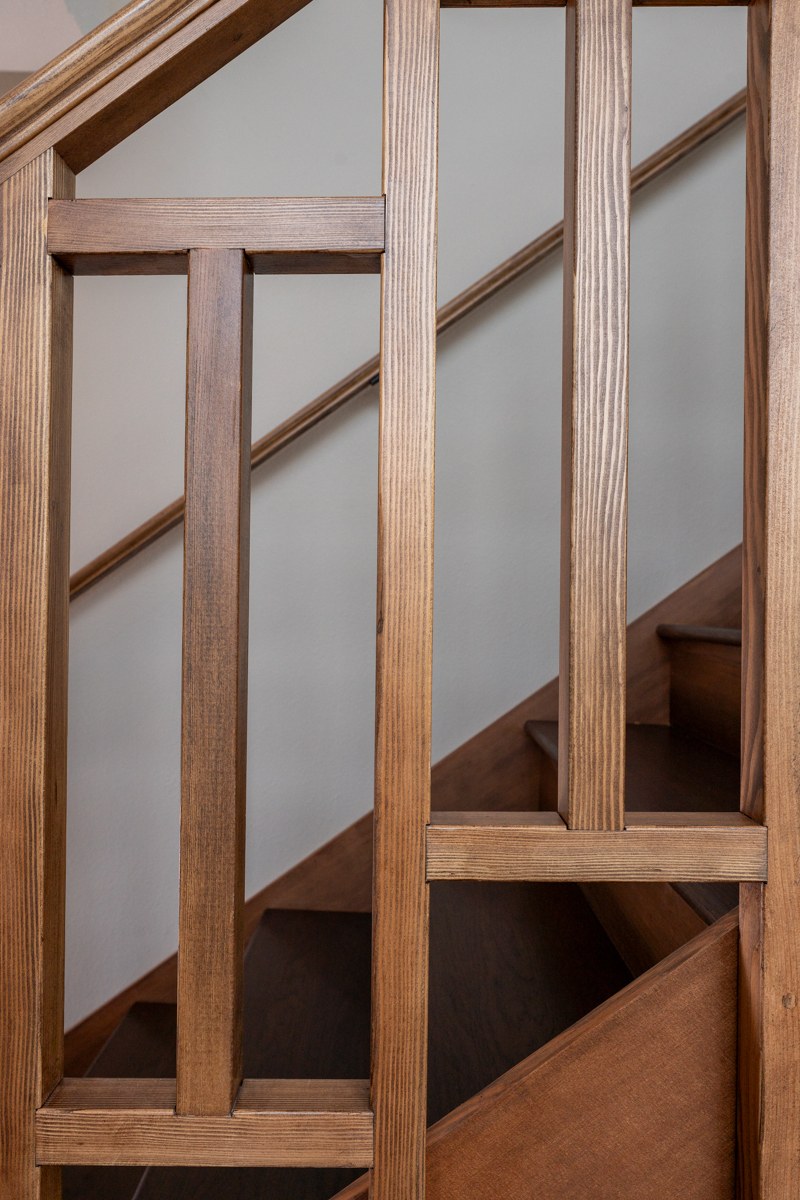
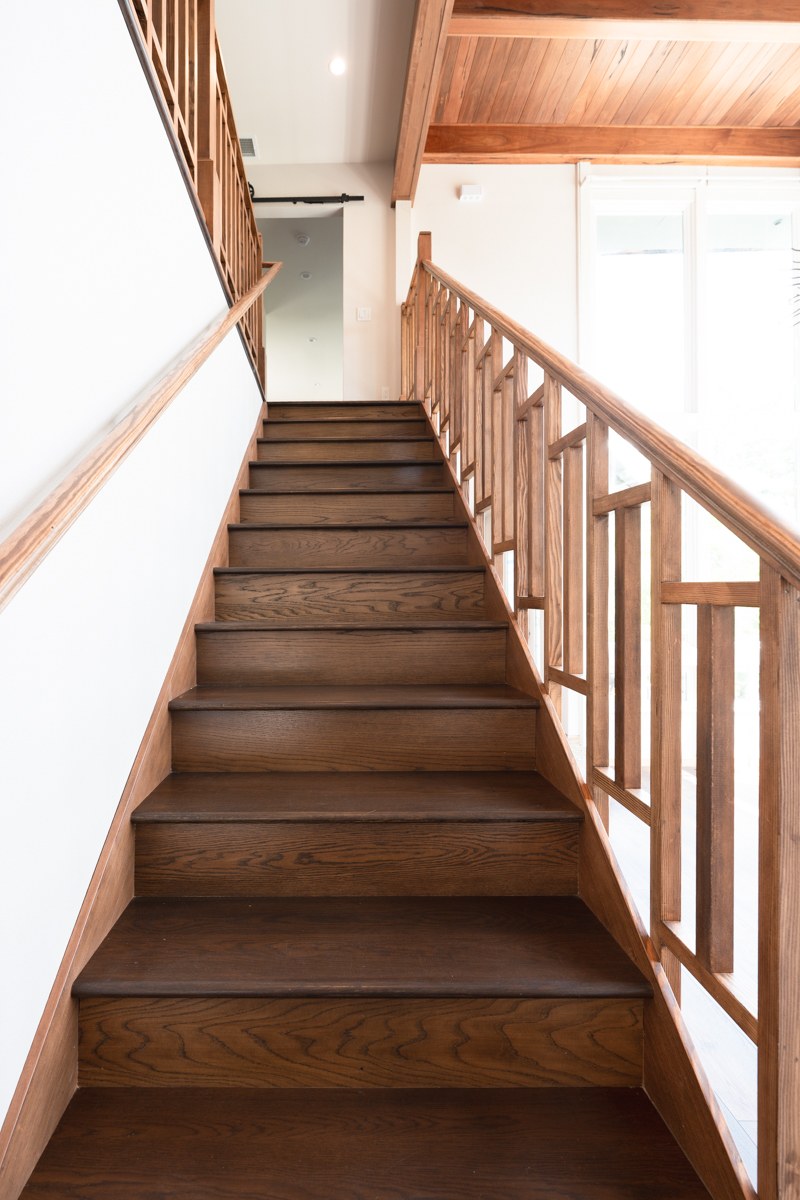

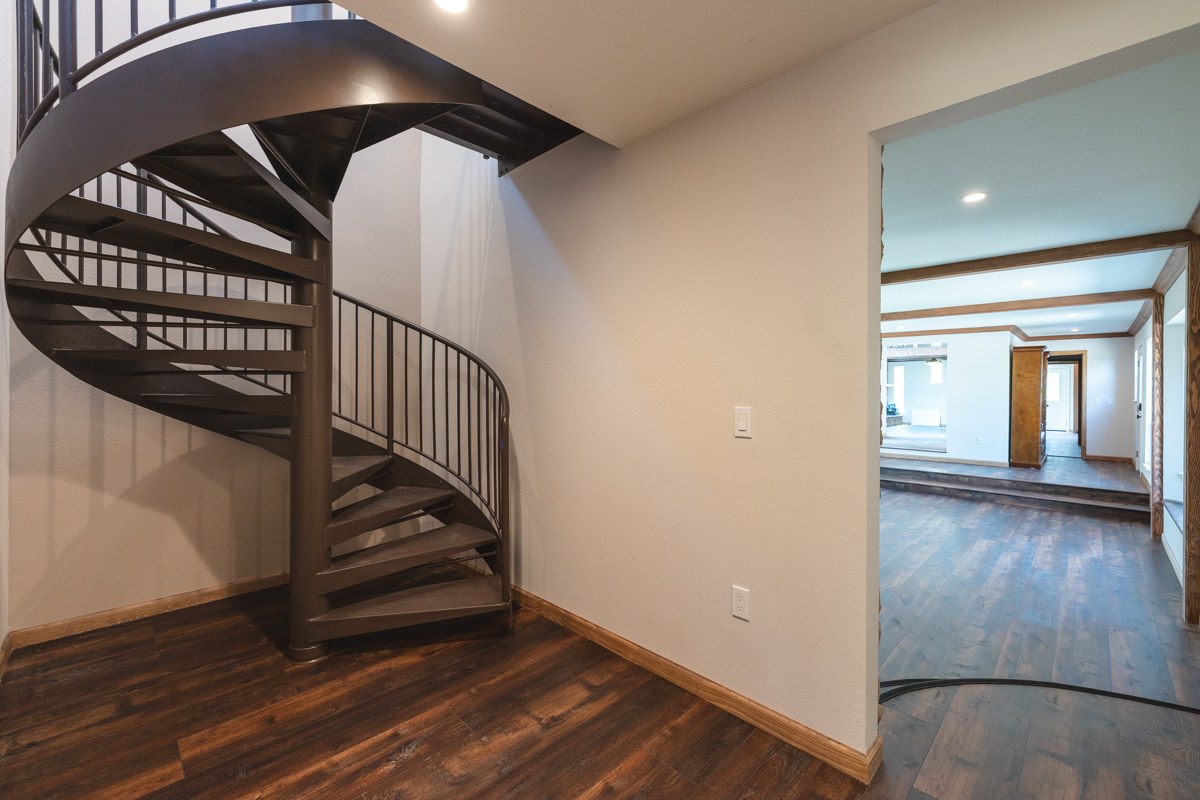
Ground-Up Custom Build
Alan Drive
Penngrove, Sonoma County
Proof we can deliver a finished home from cleared dirt — when the rebuild calls for new construction.
Not a fire rebuild — but a useful proof point for adjusters considering us for total-loss projects where the homeowner wants something different than what was lost. Ground-up custom on 2+ acres, photographed at every milestone. We run the same process whether the cause was fire, flood, or a vacant lot.
Lot
2+ acres
Build
Ground-Up Custom
Documentation
Every Milestone


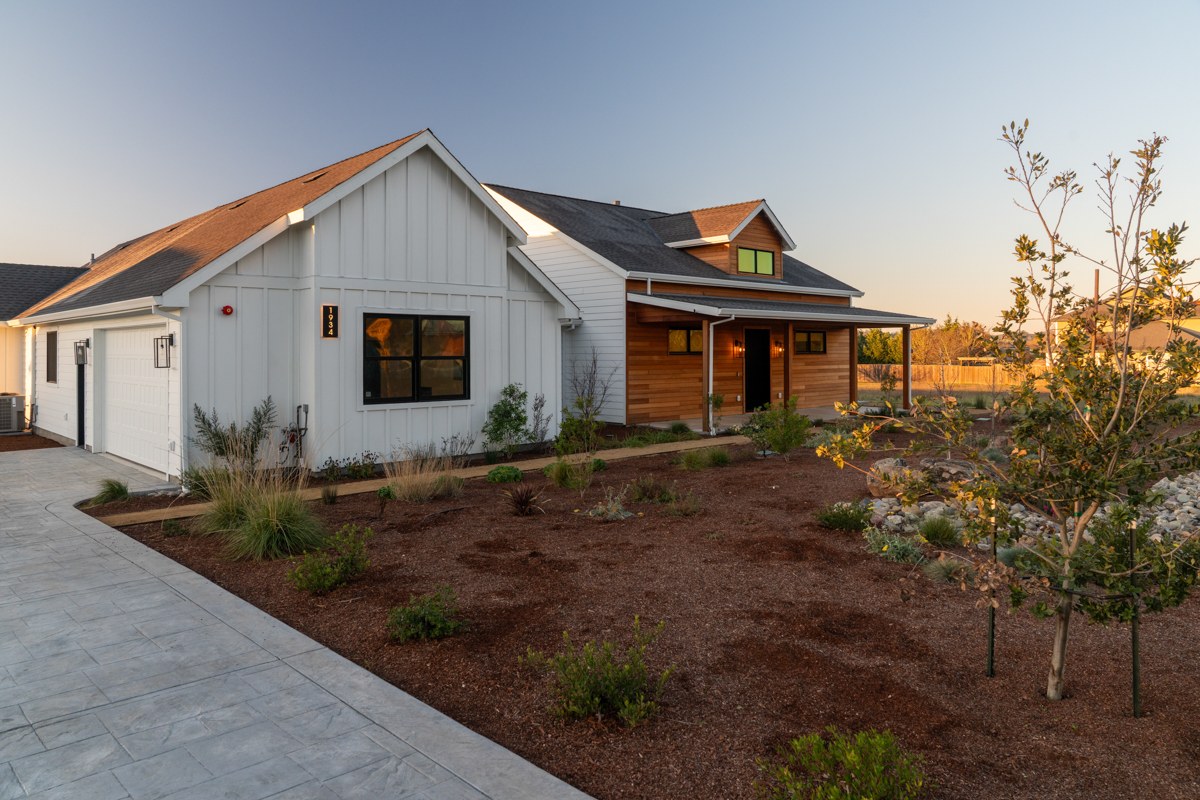
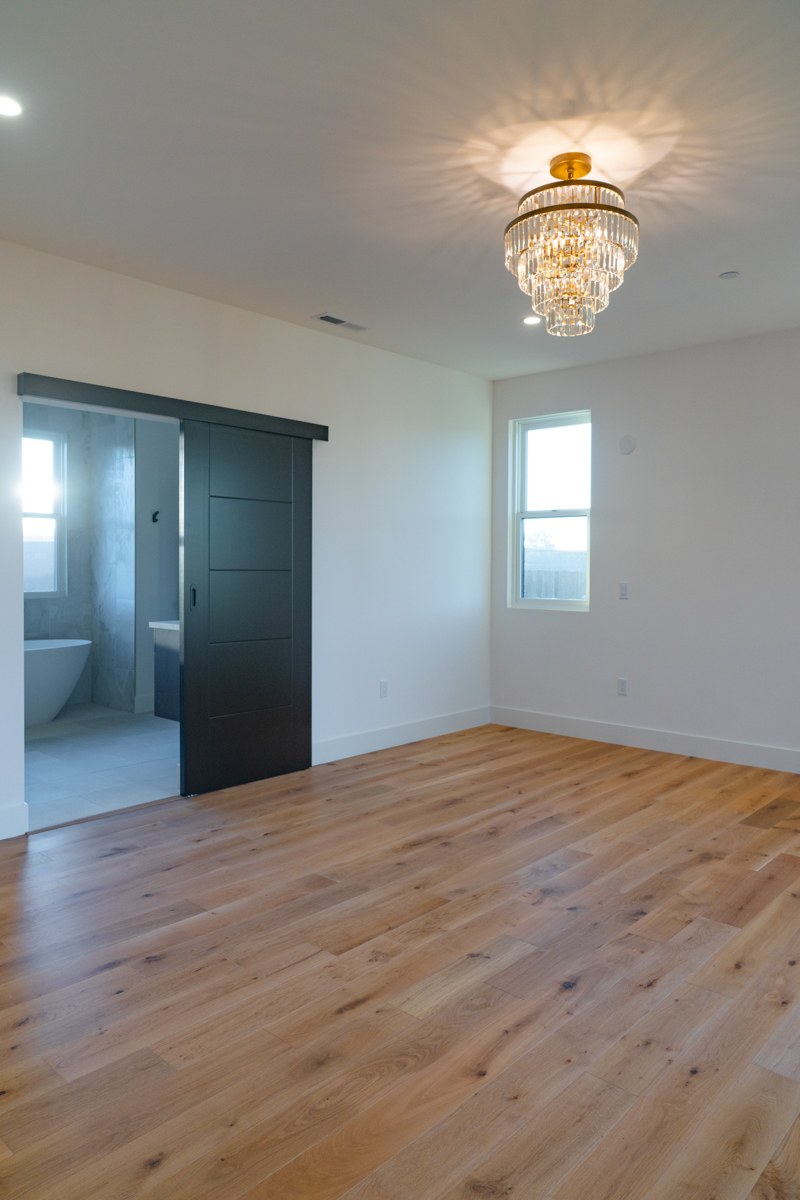
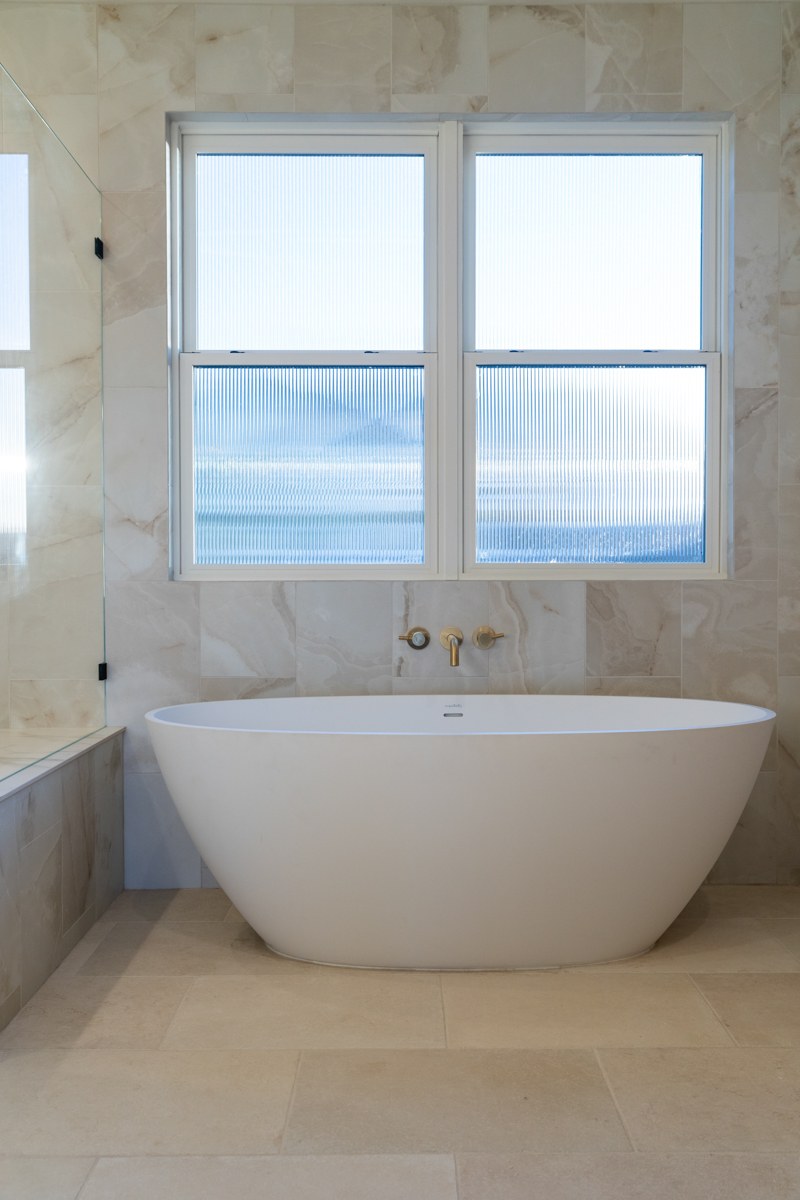
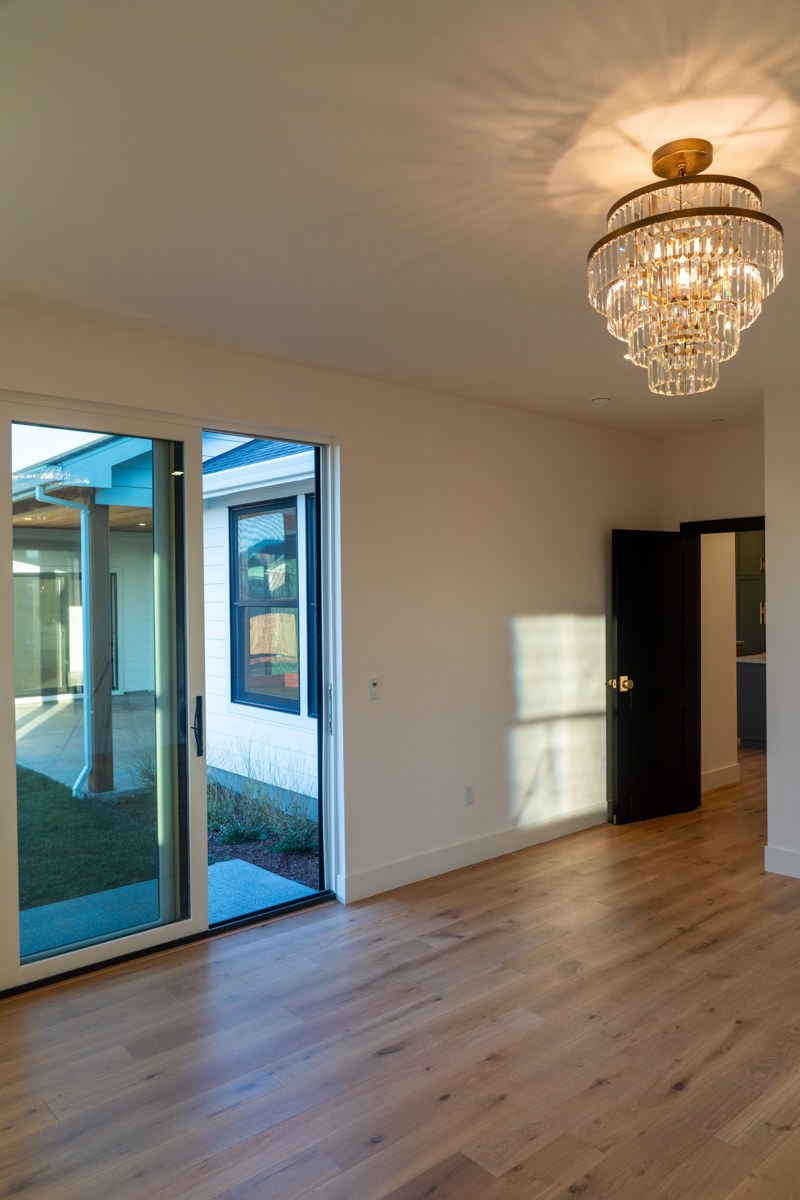

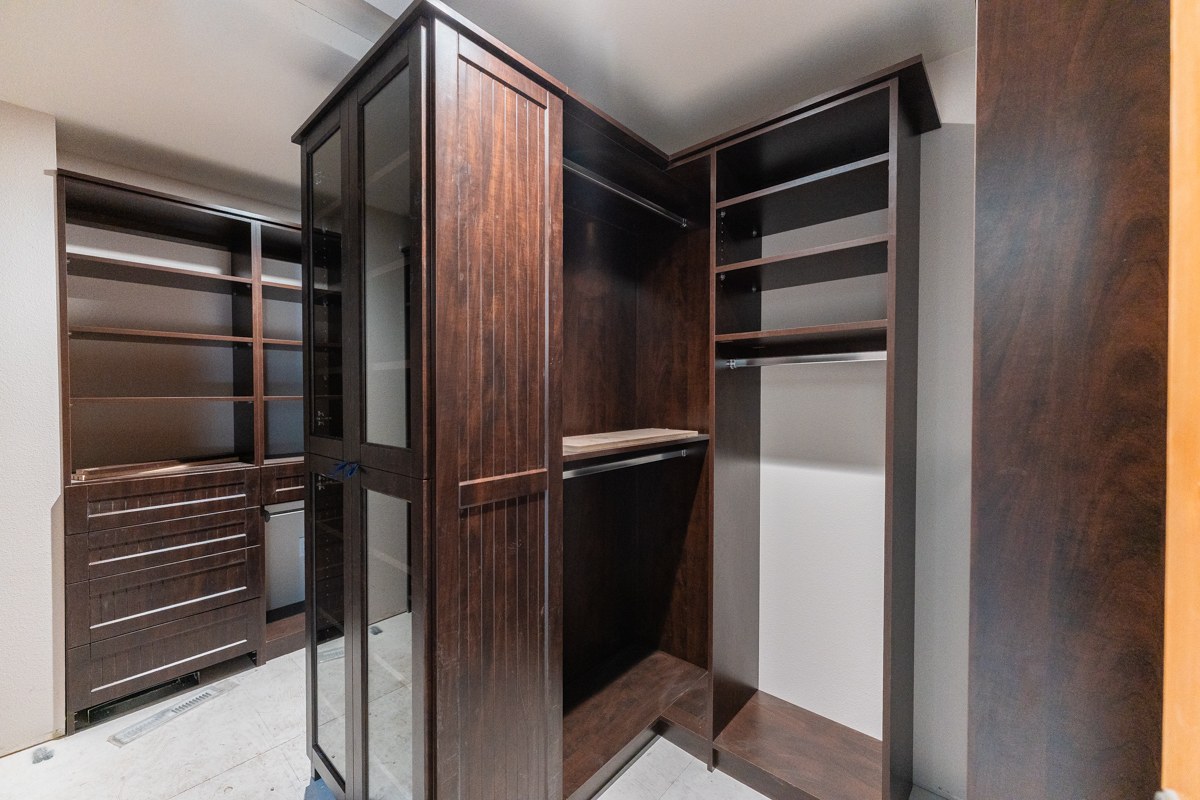
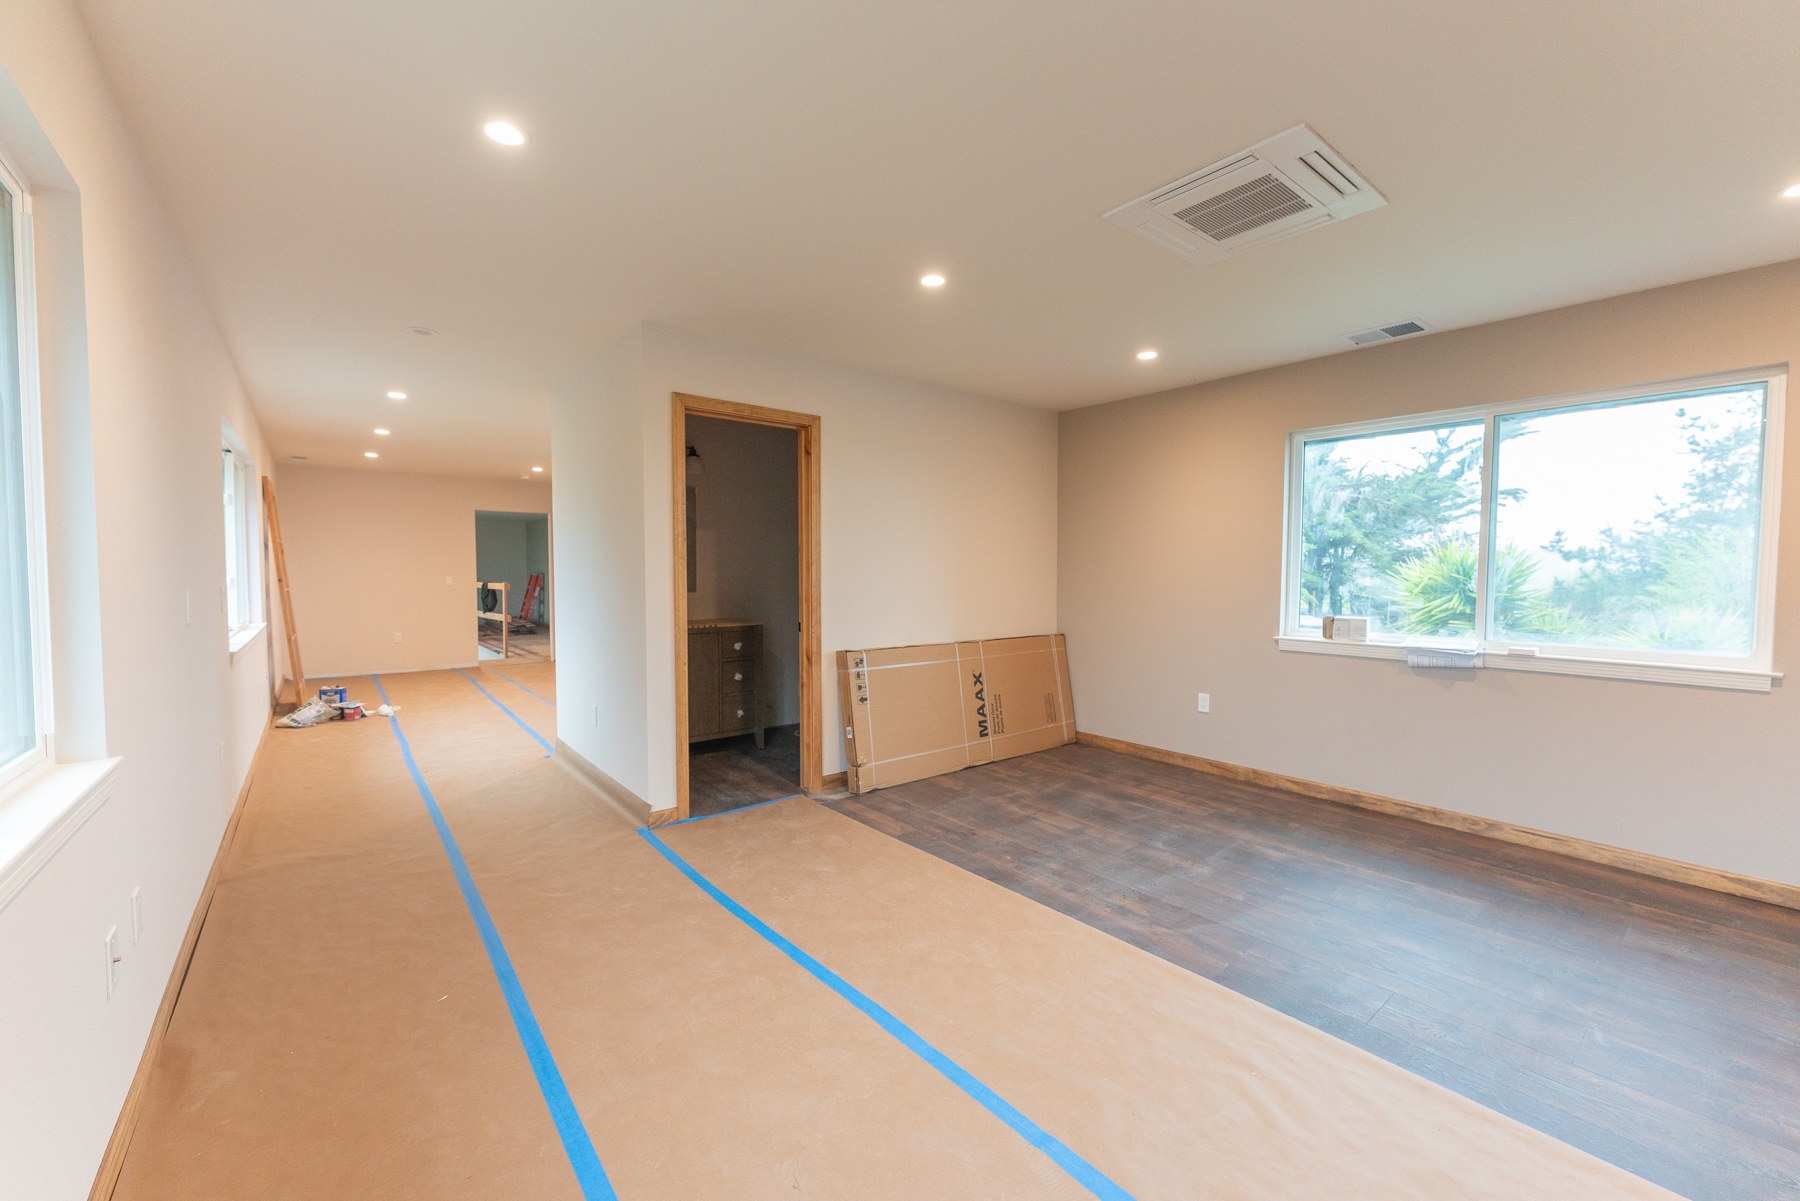
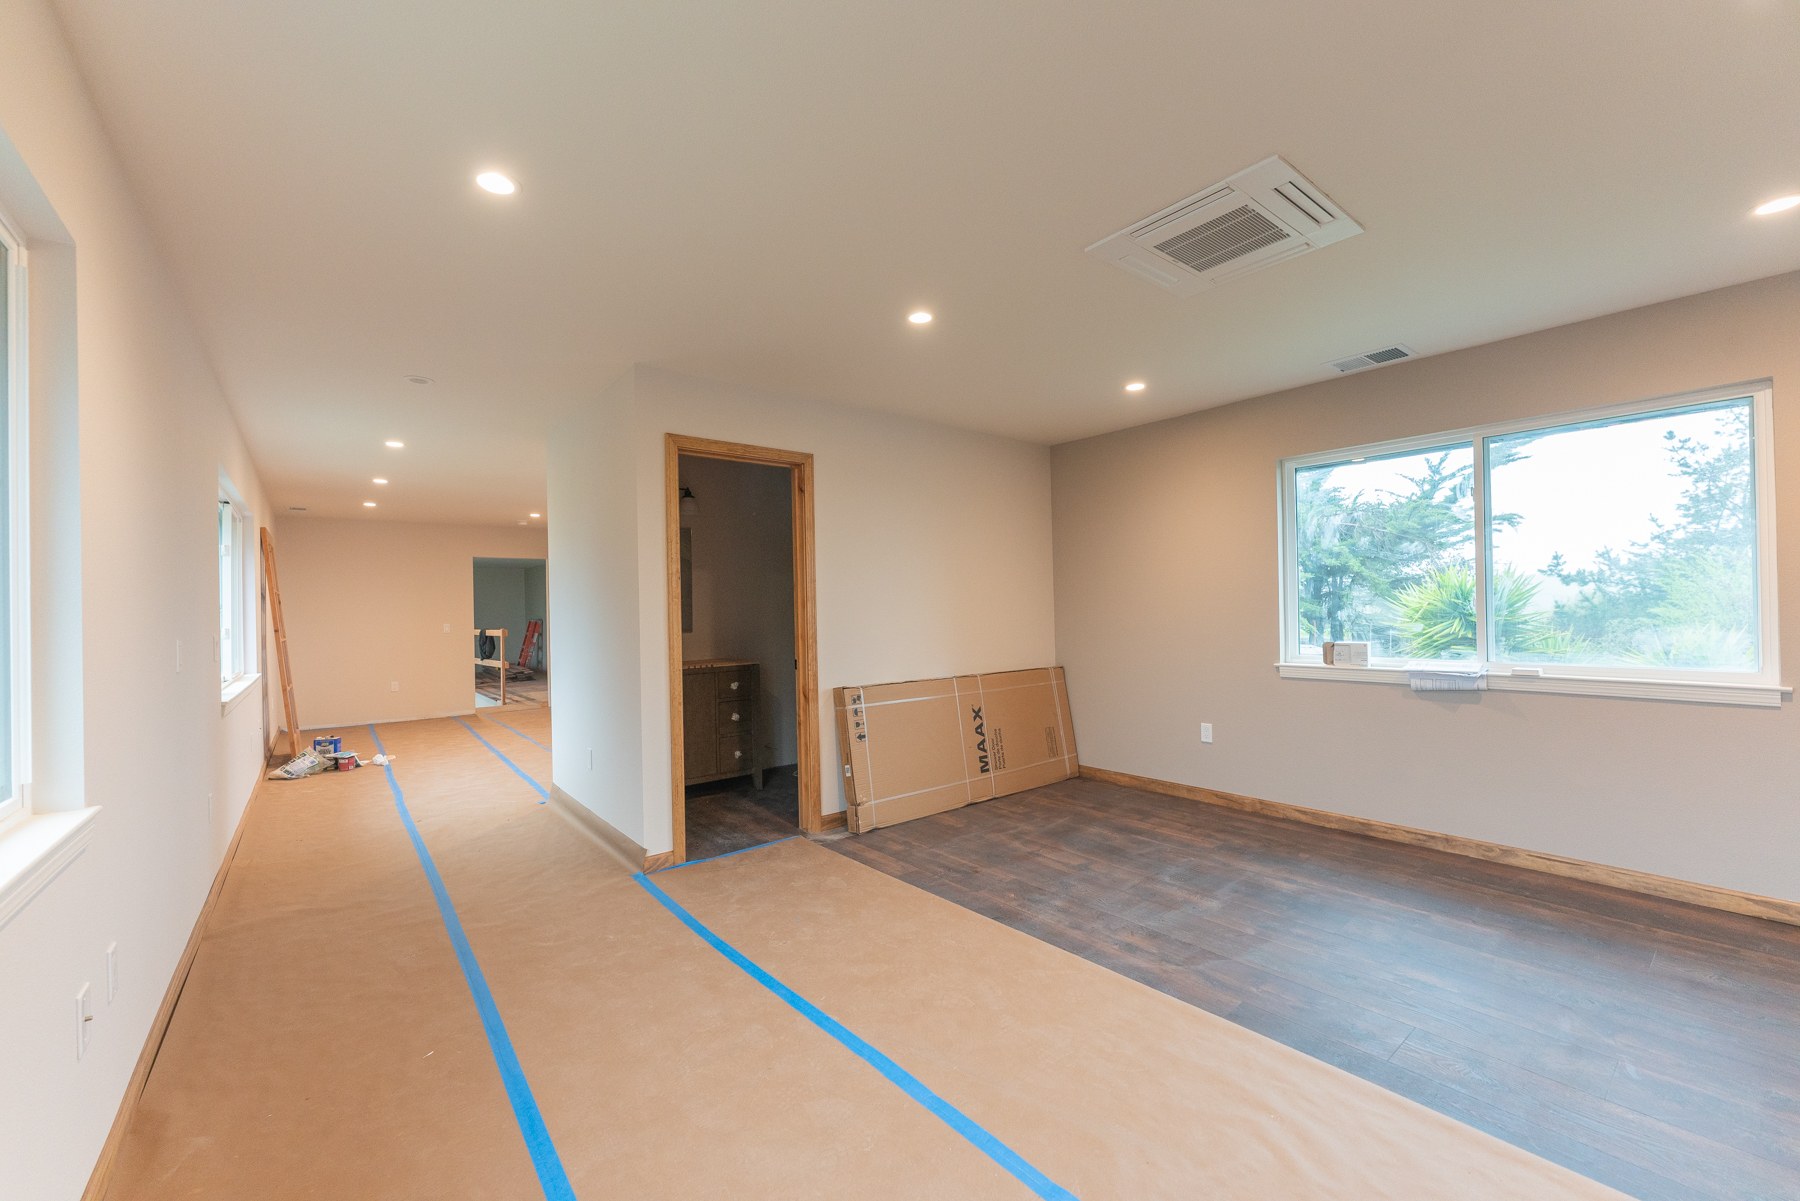
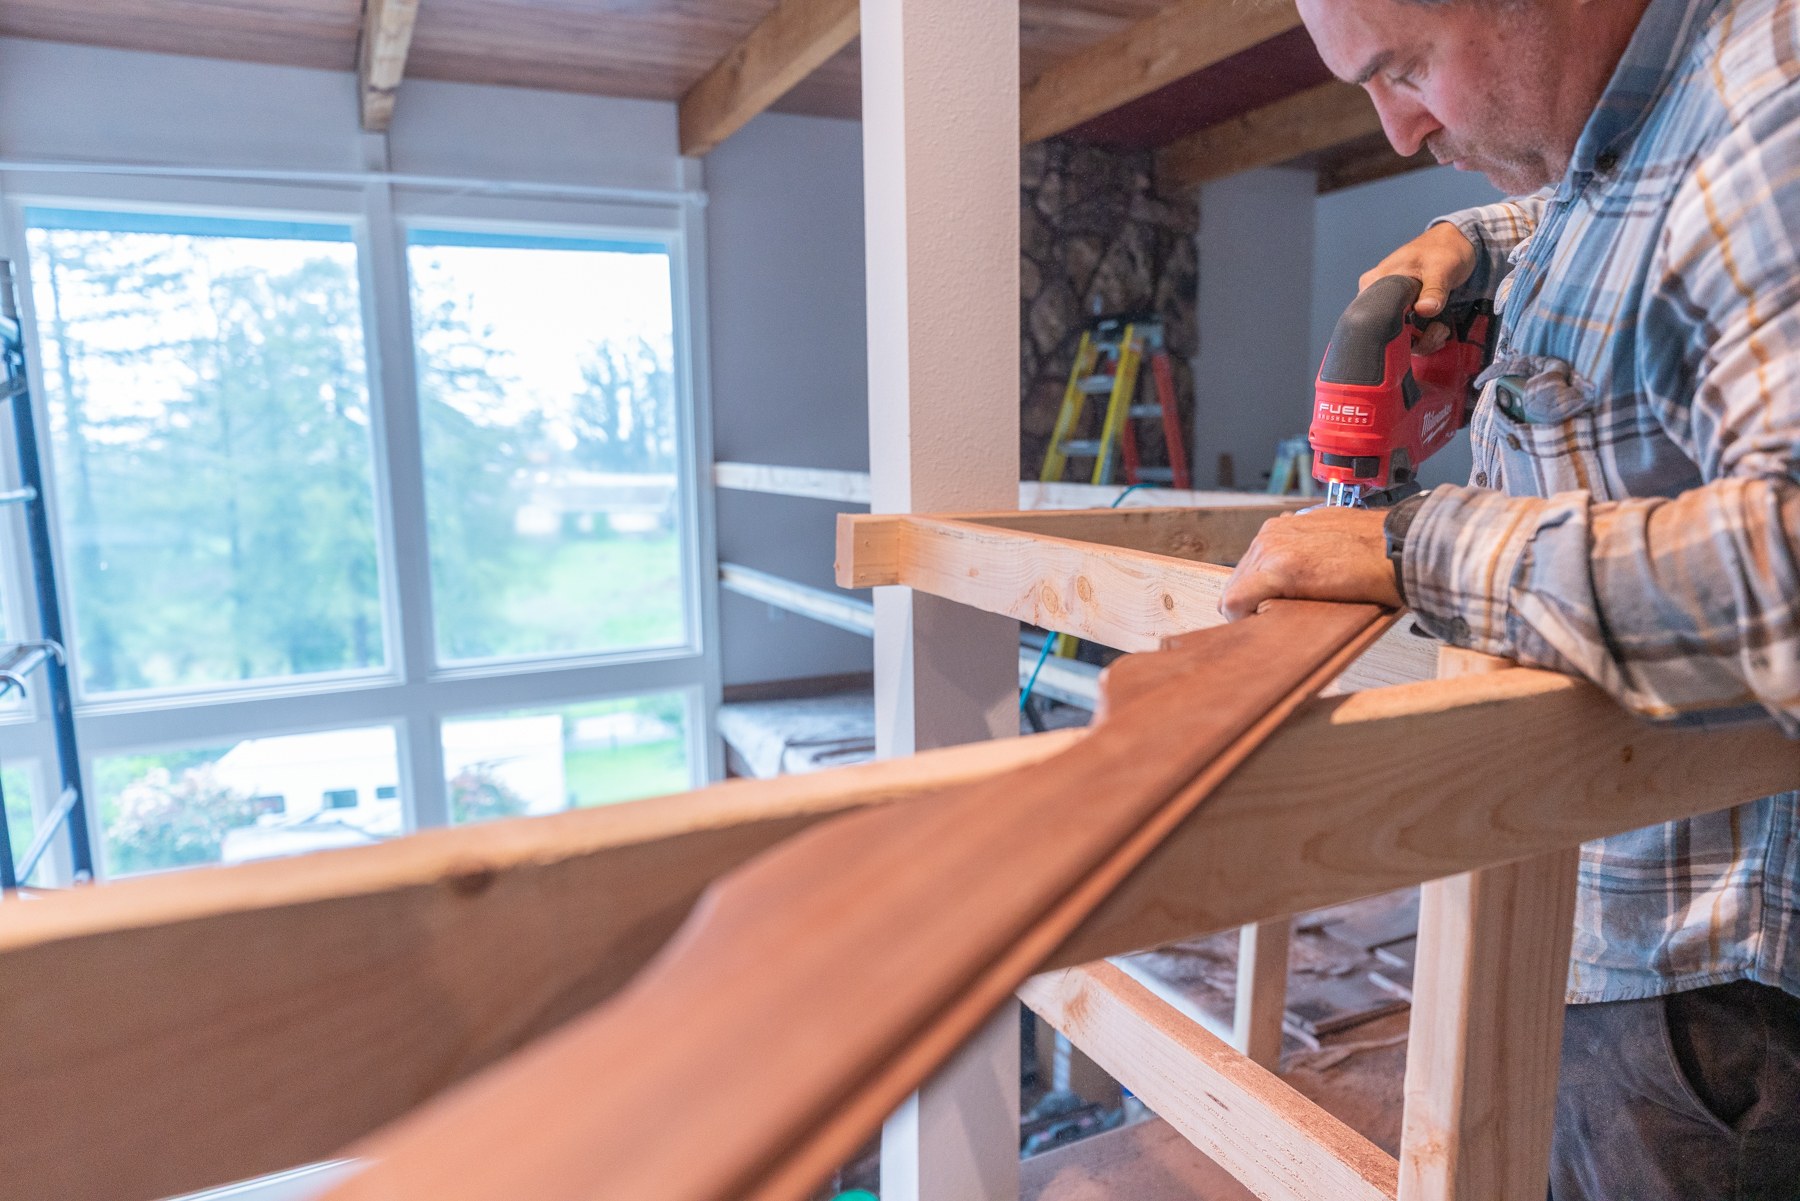
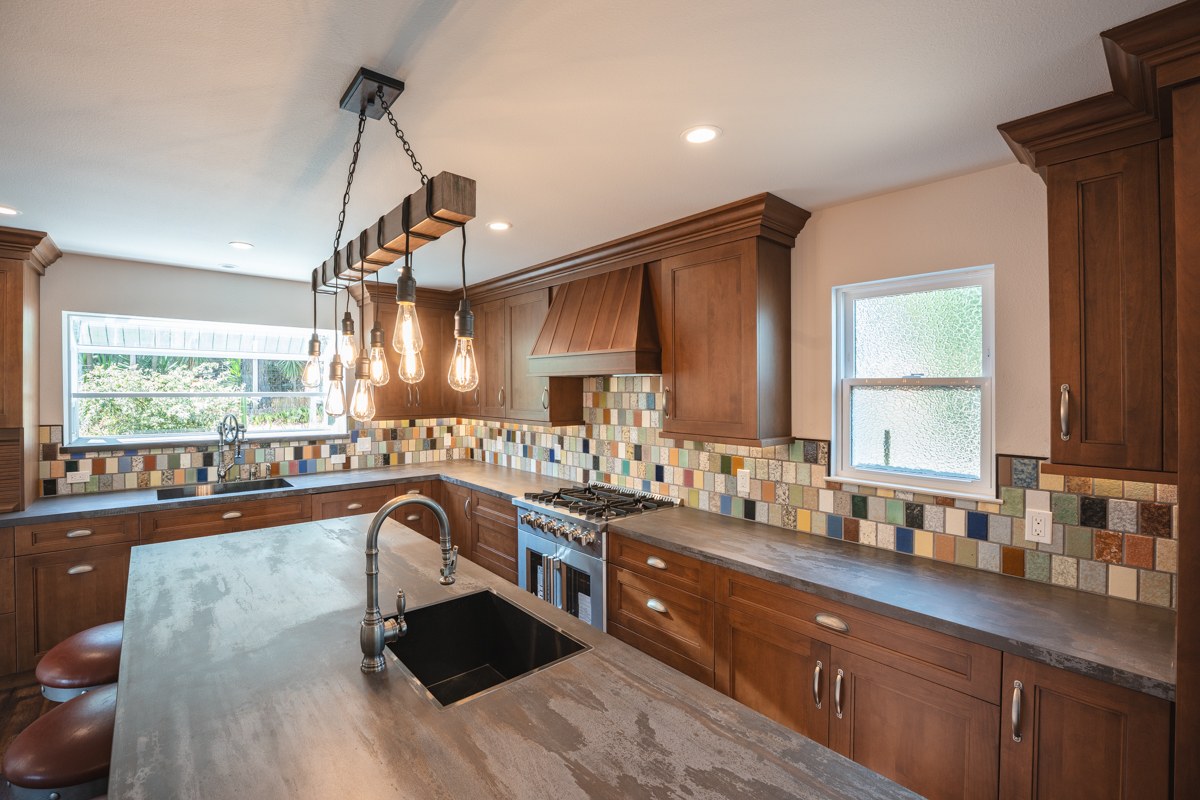
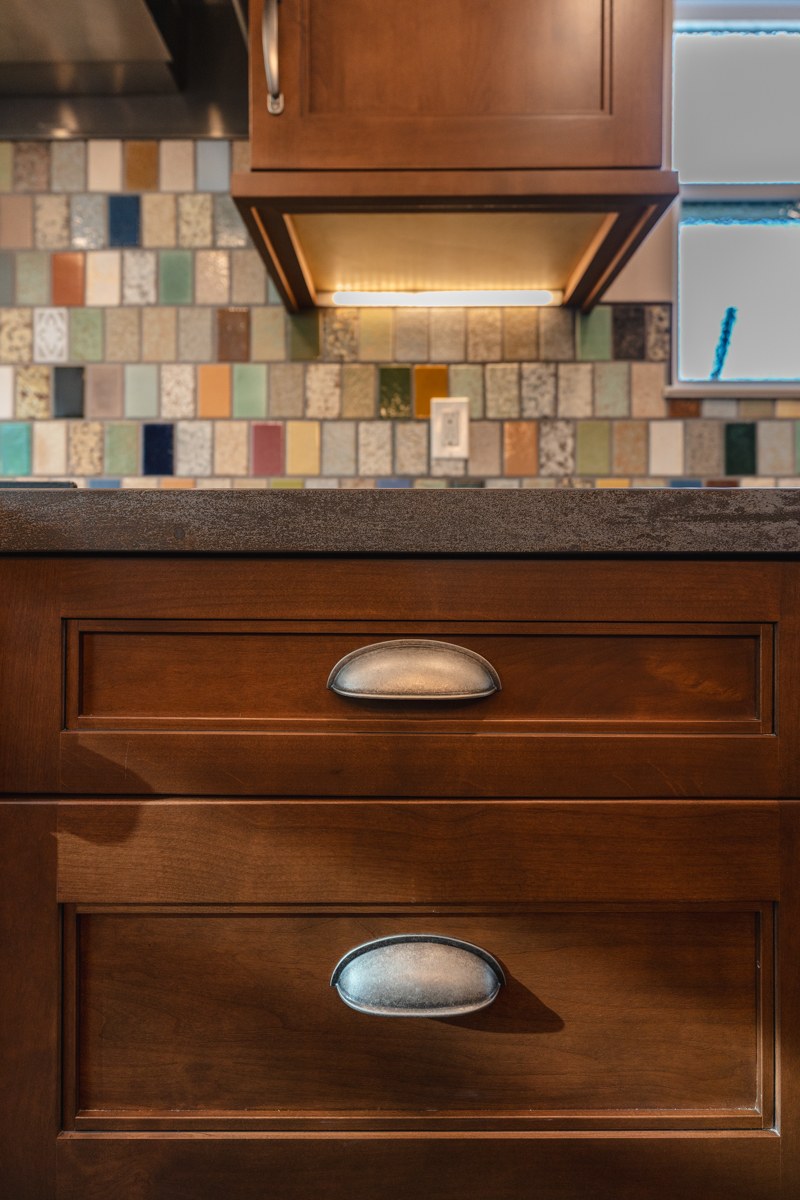
Restoration & Rebuild Work
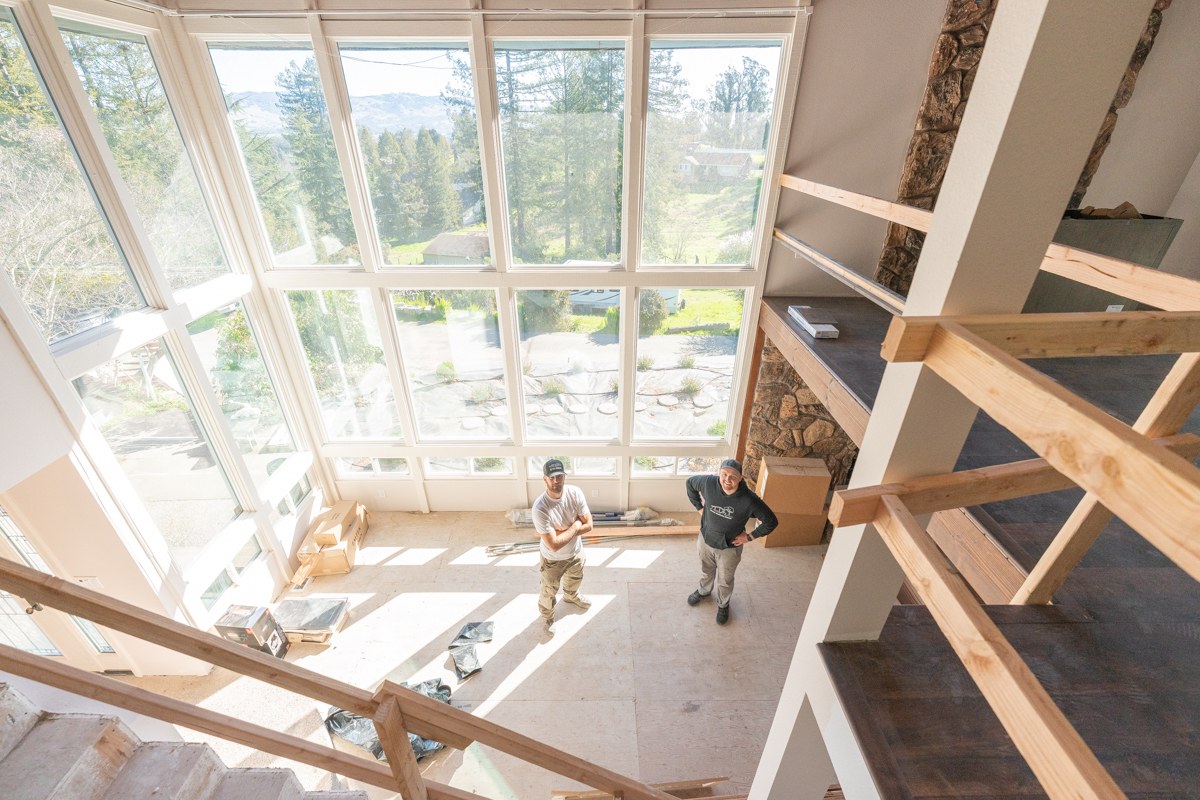
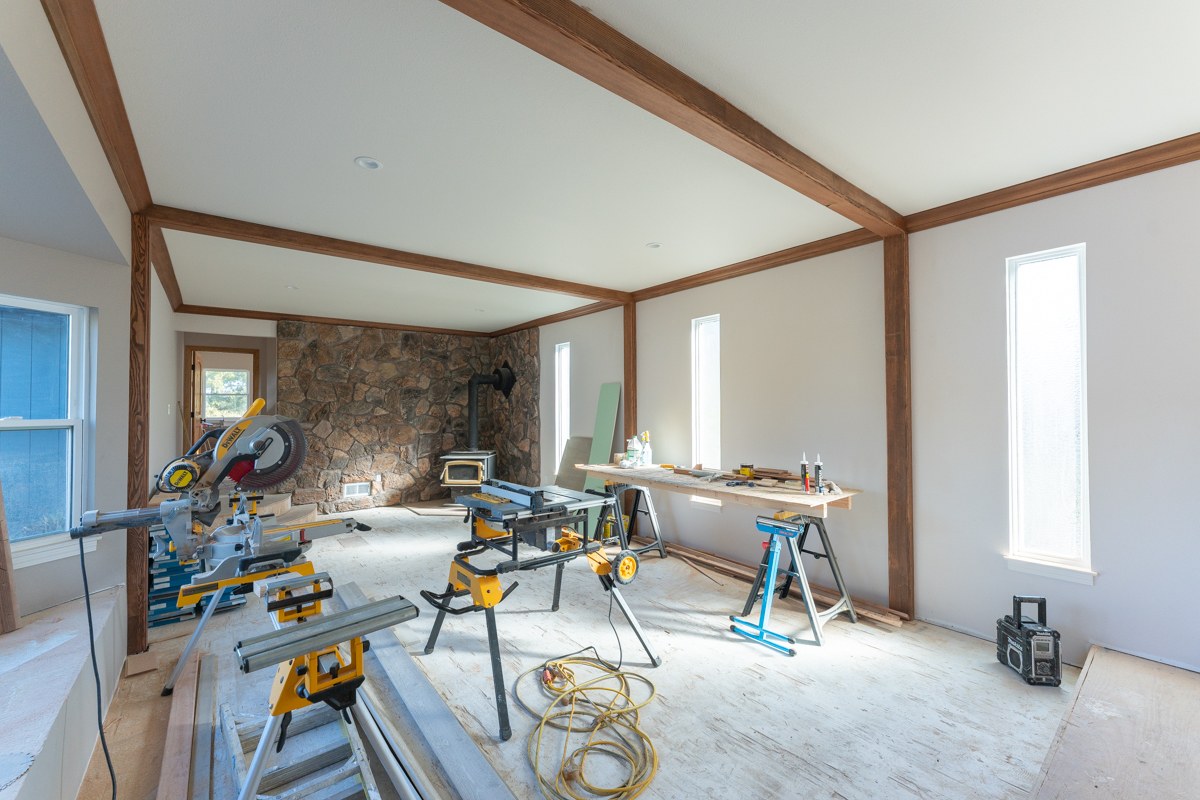
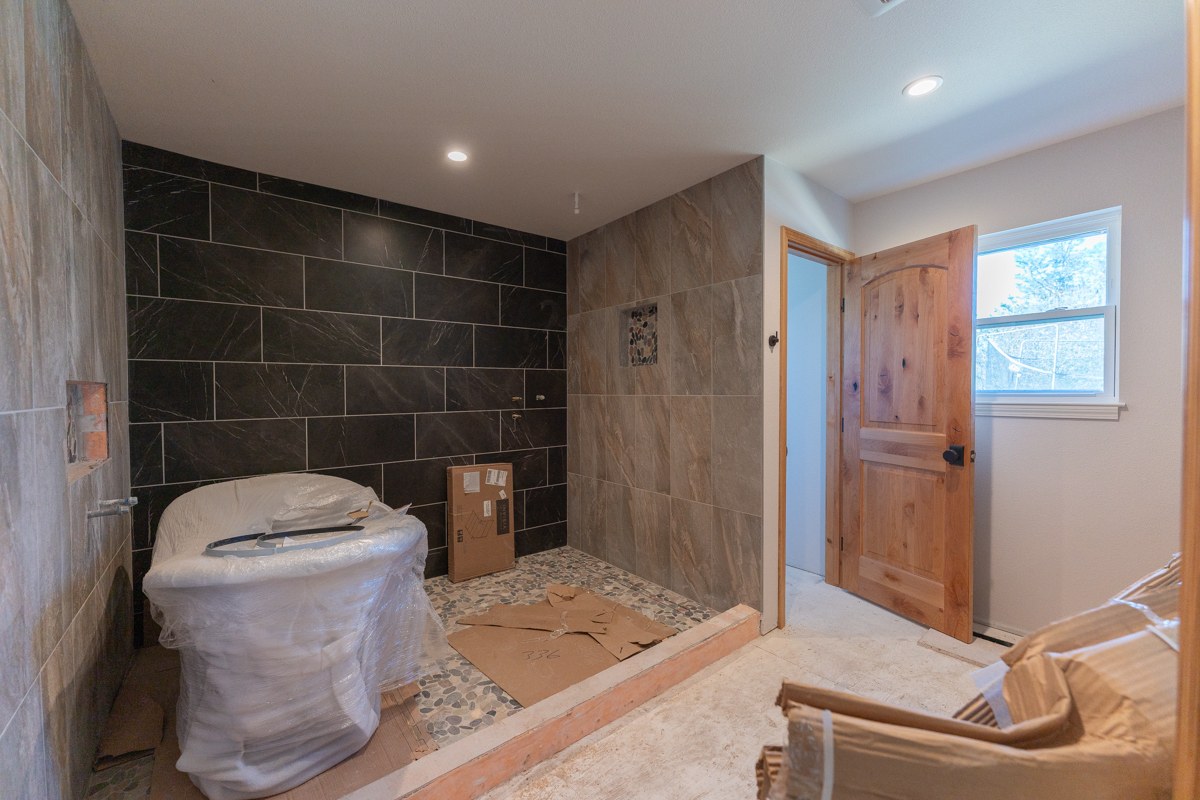
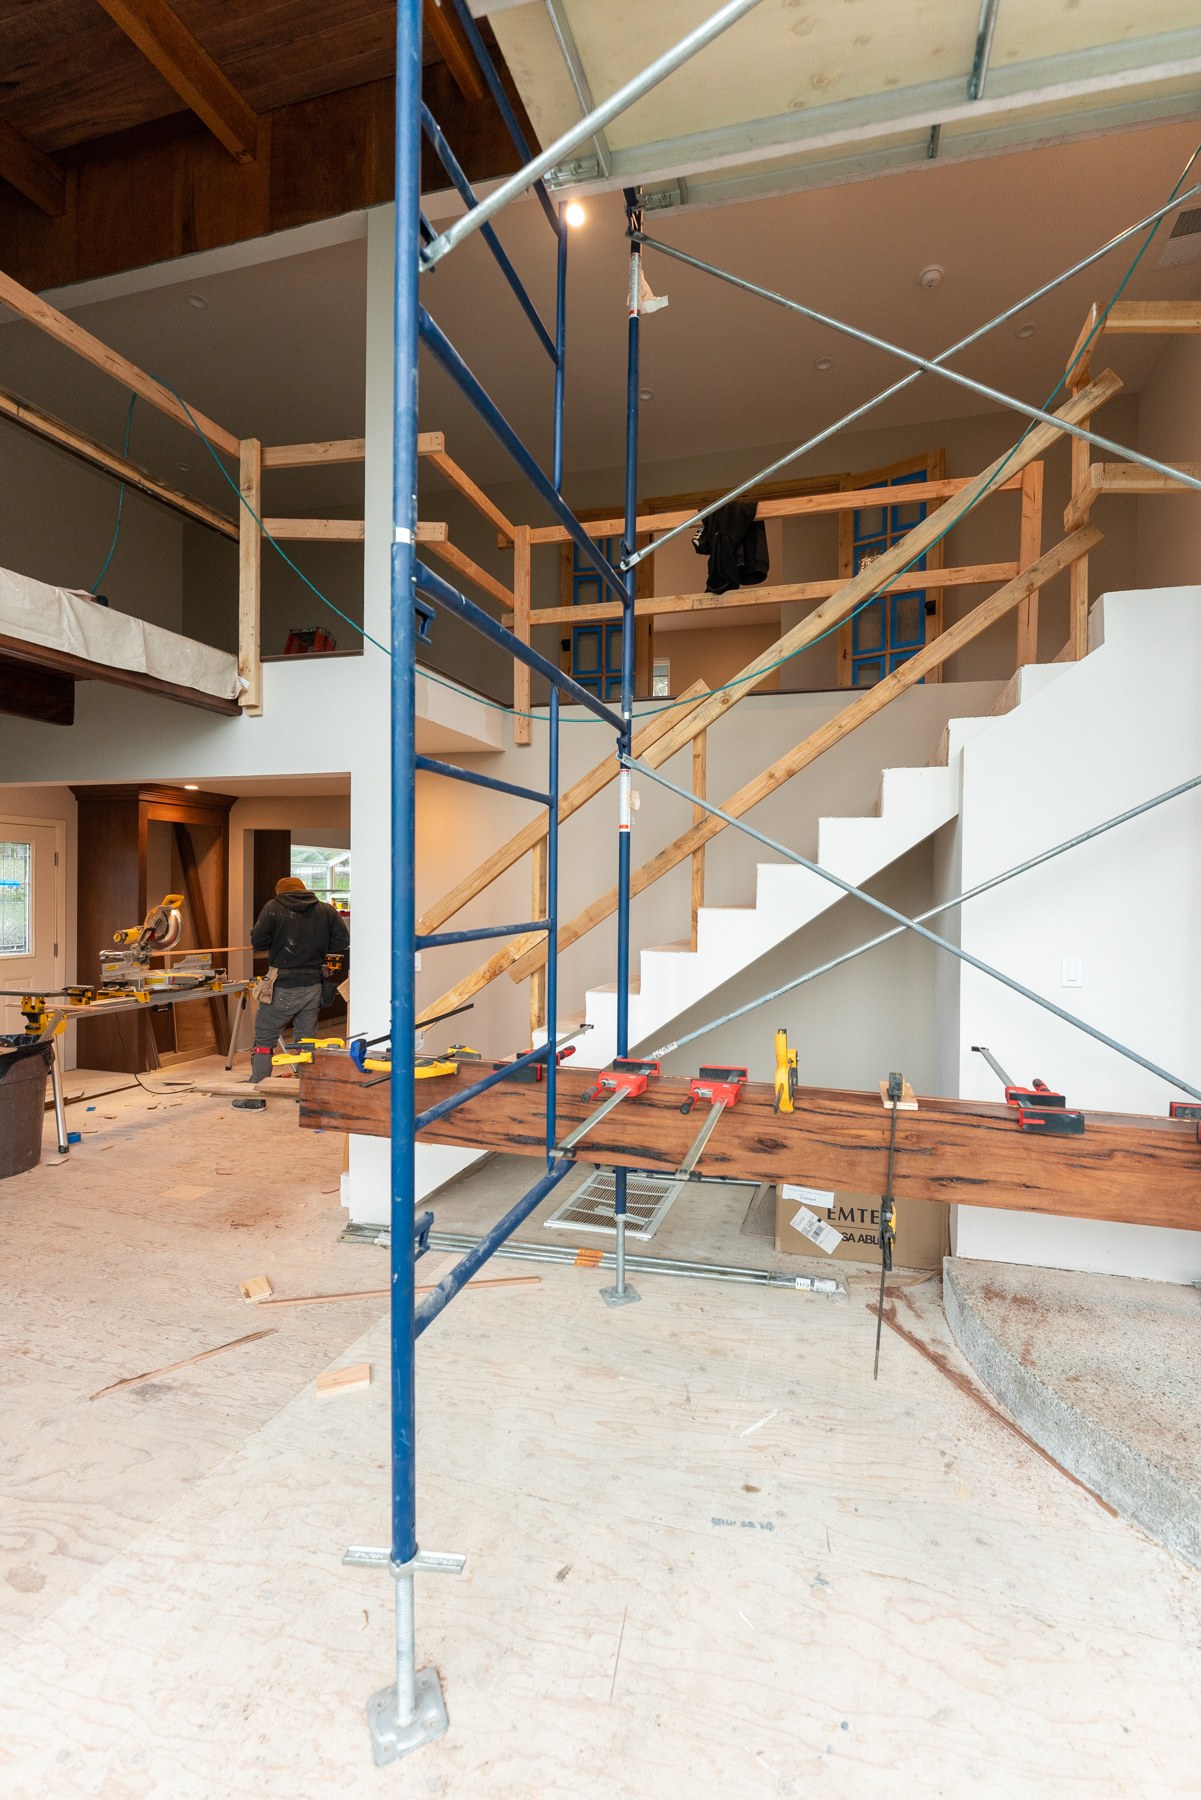
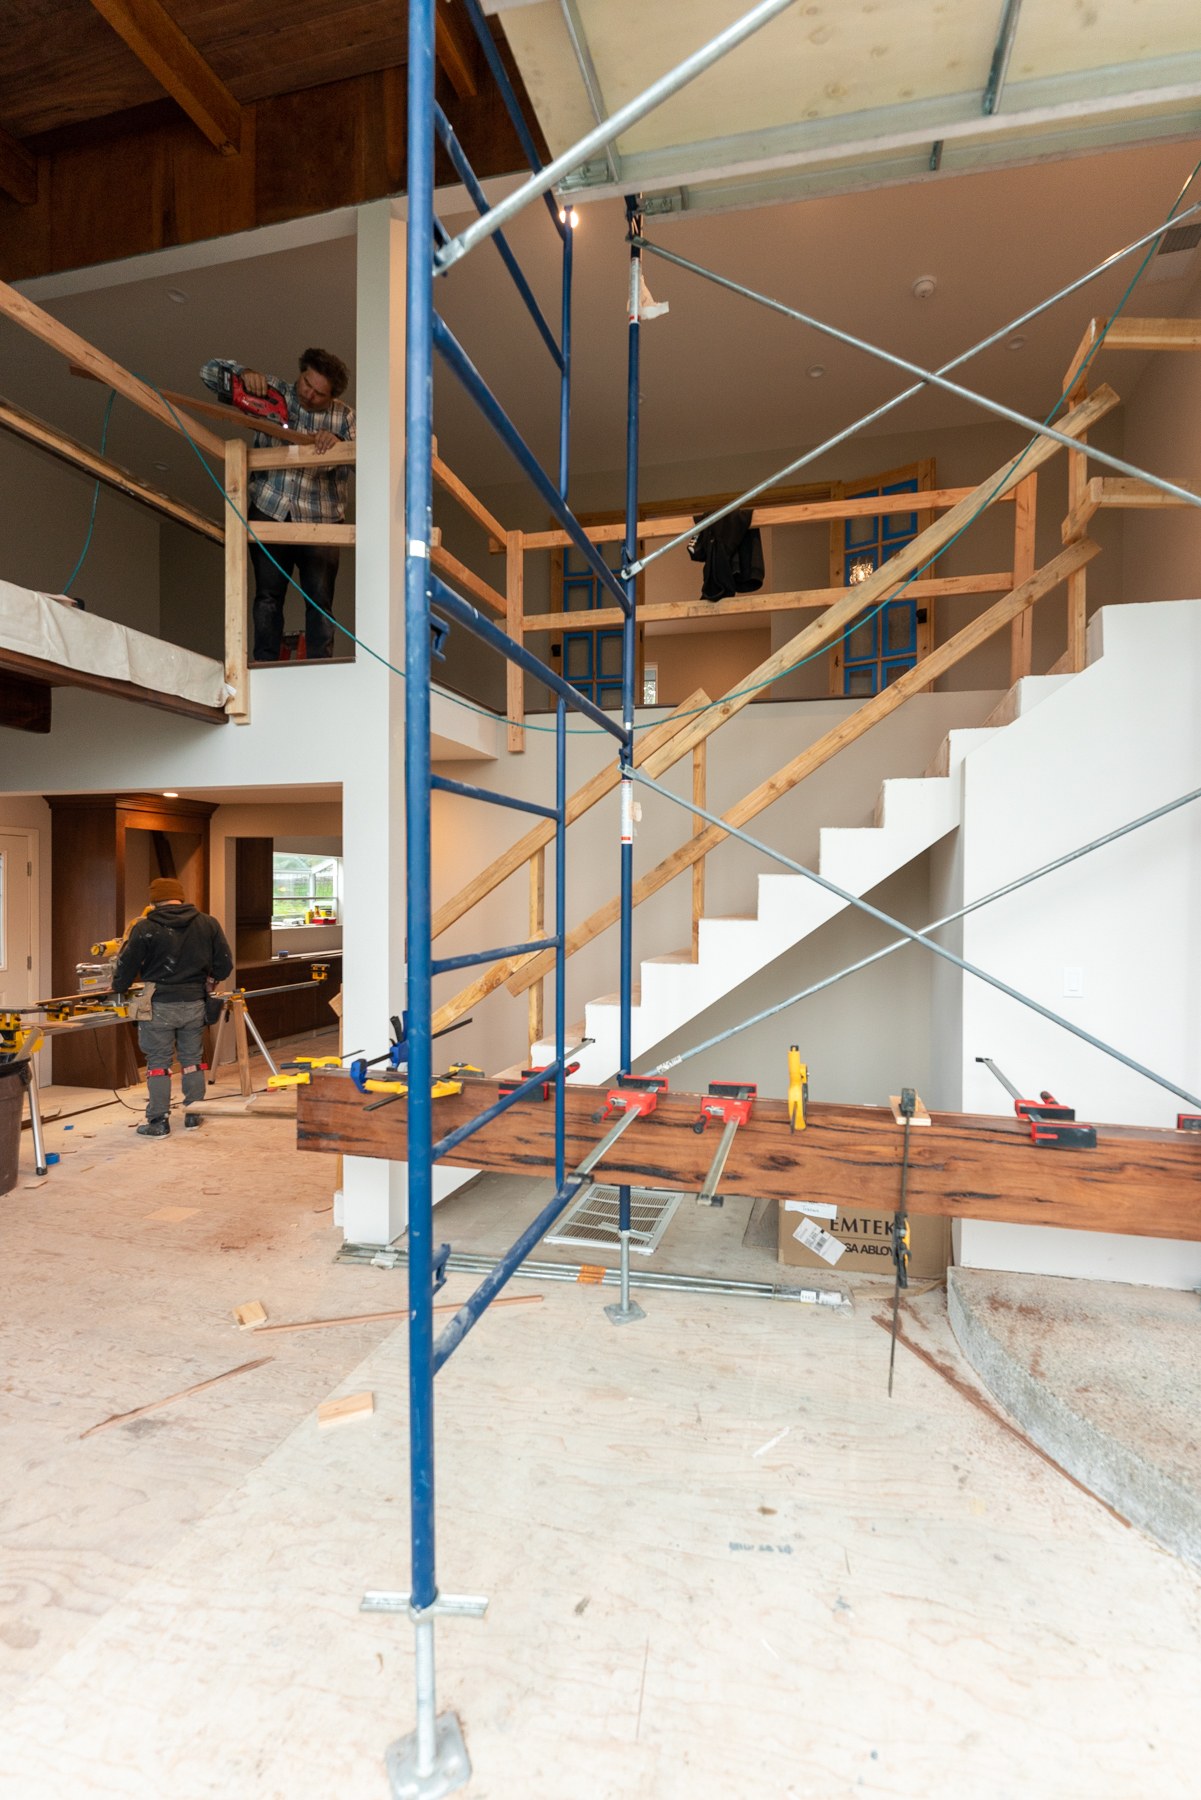
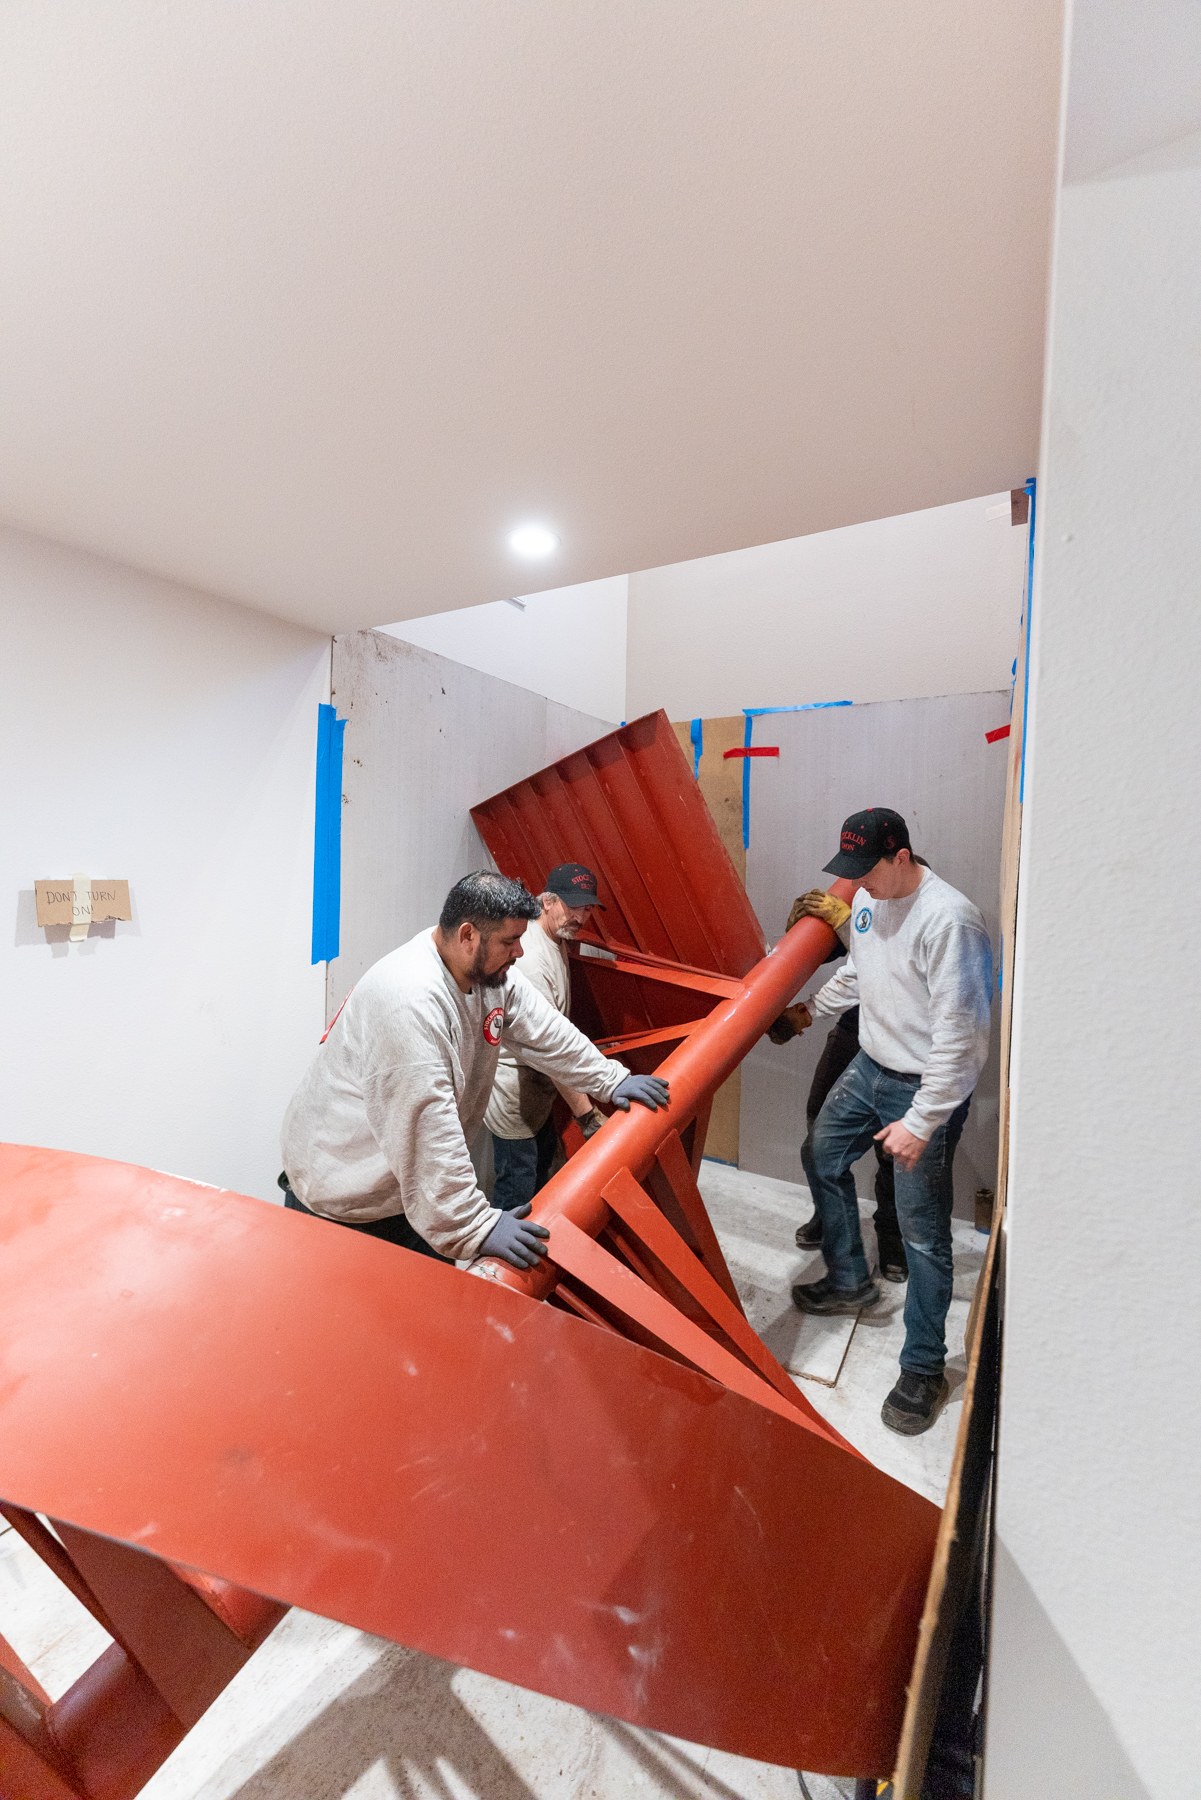
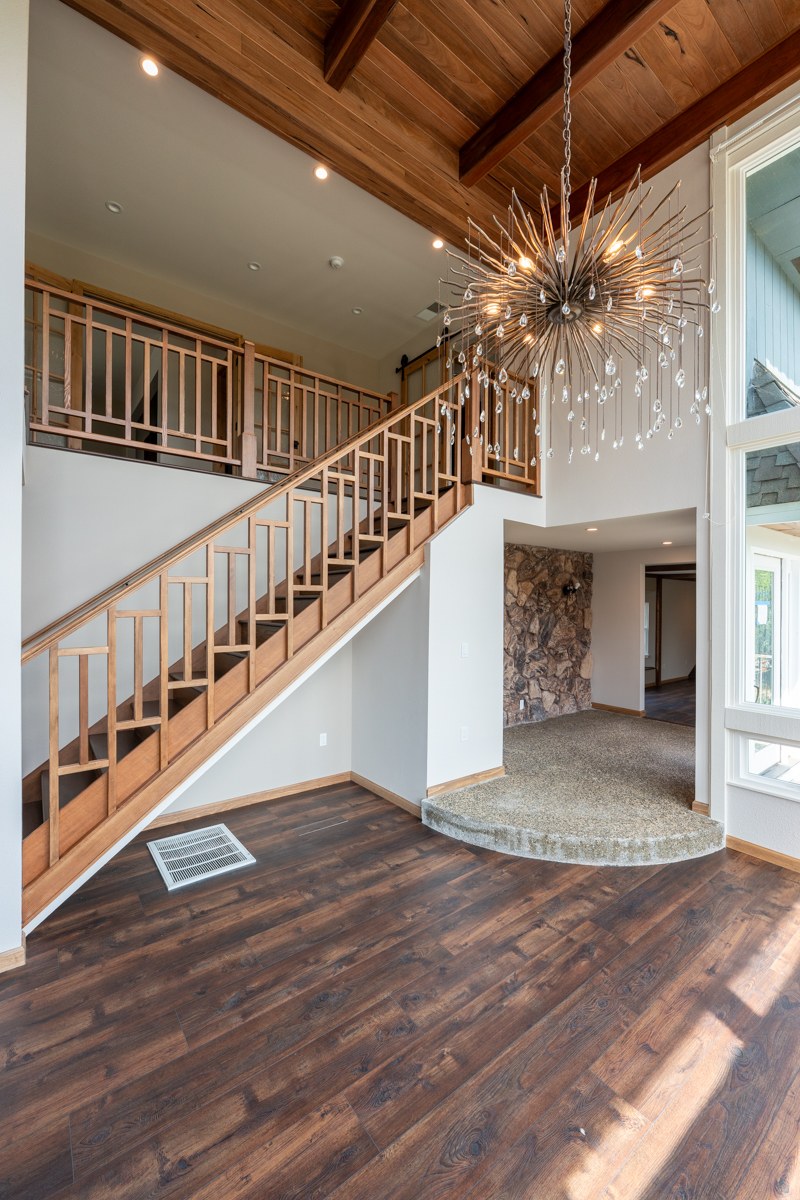
A wider look at the work
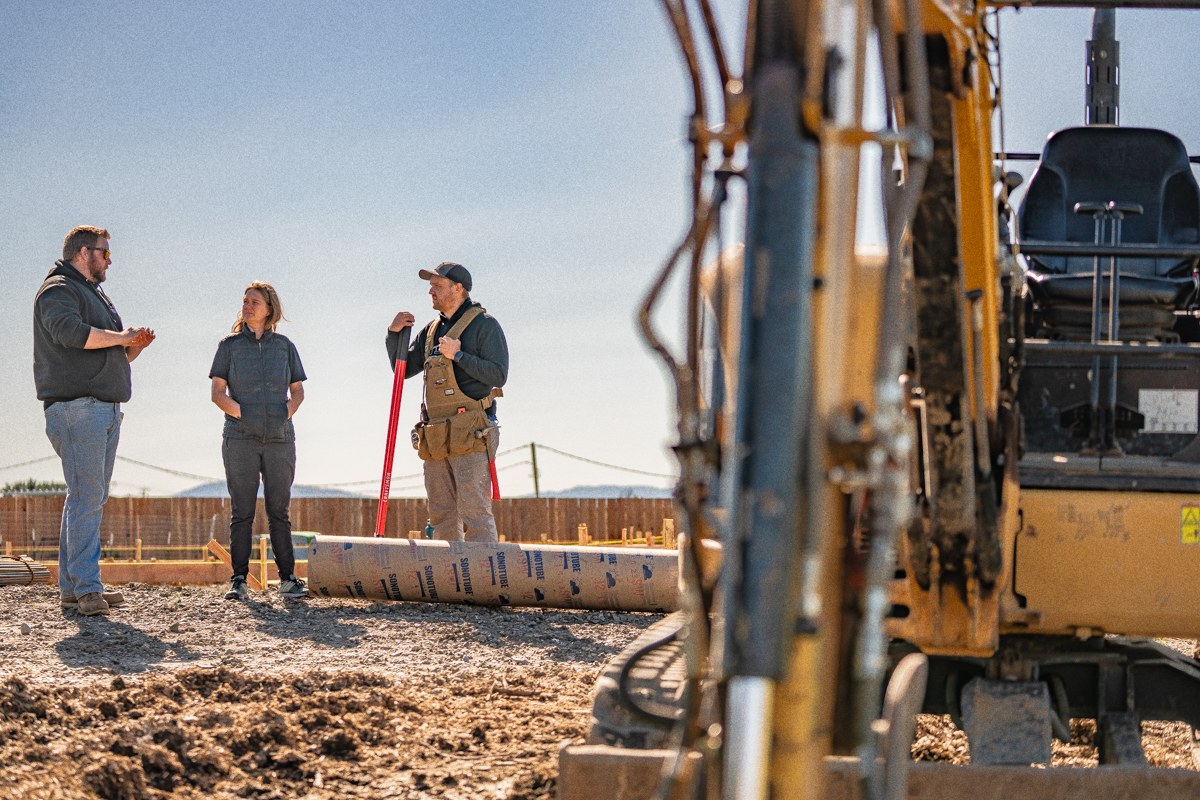
Pre-construction conditions through final walkthrough. Every phase documented in-house — the file the adjuster relies on starts with what we capture on site.

Who Runs SRS
Kelly + Ryan
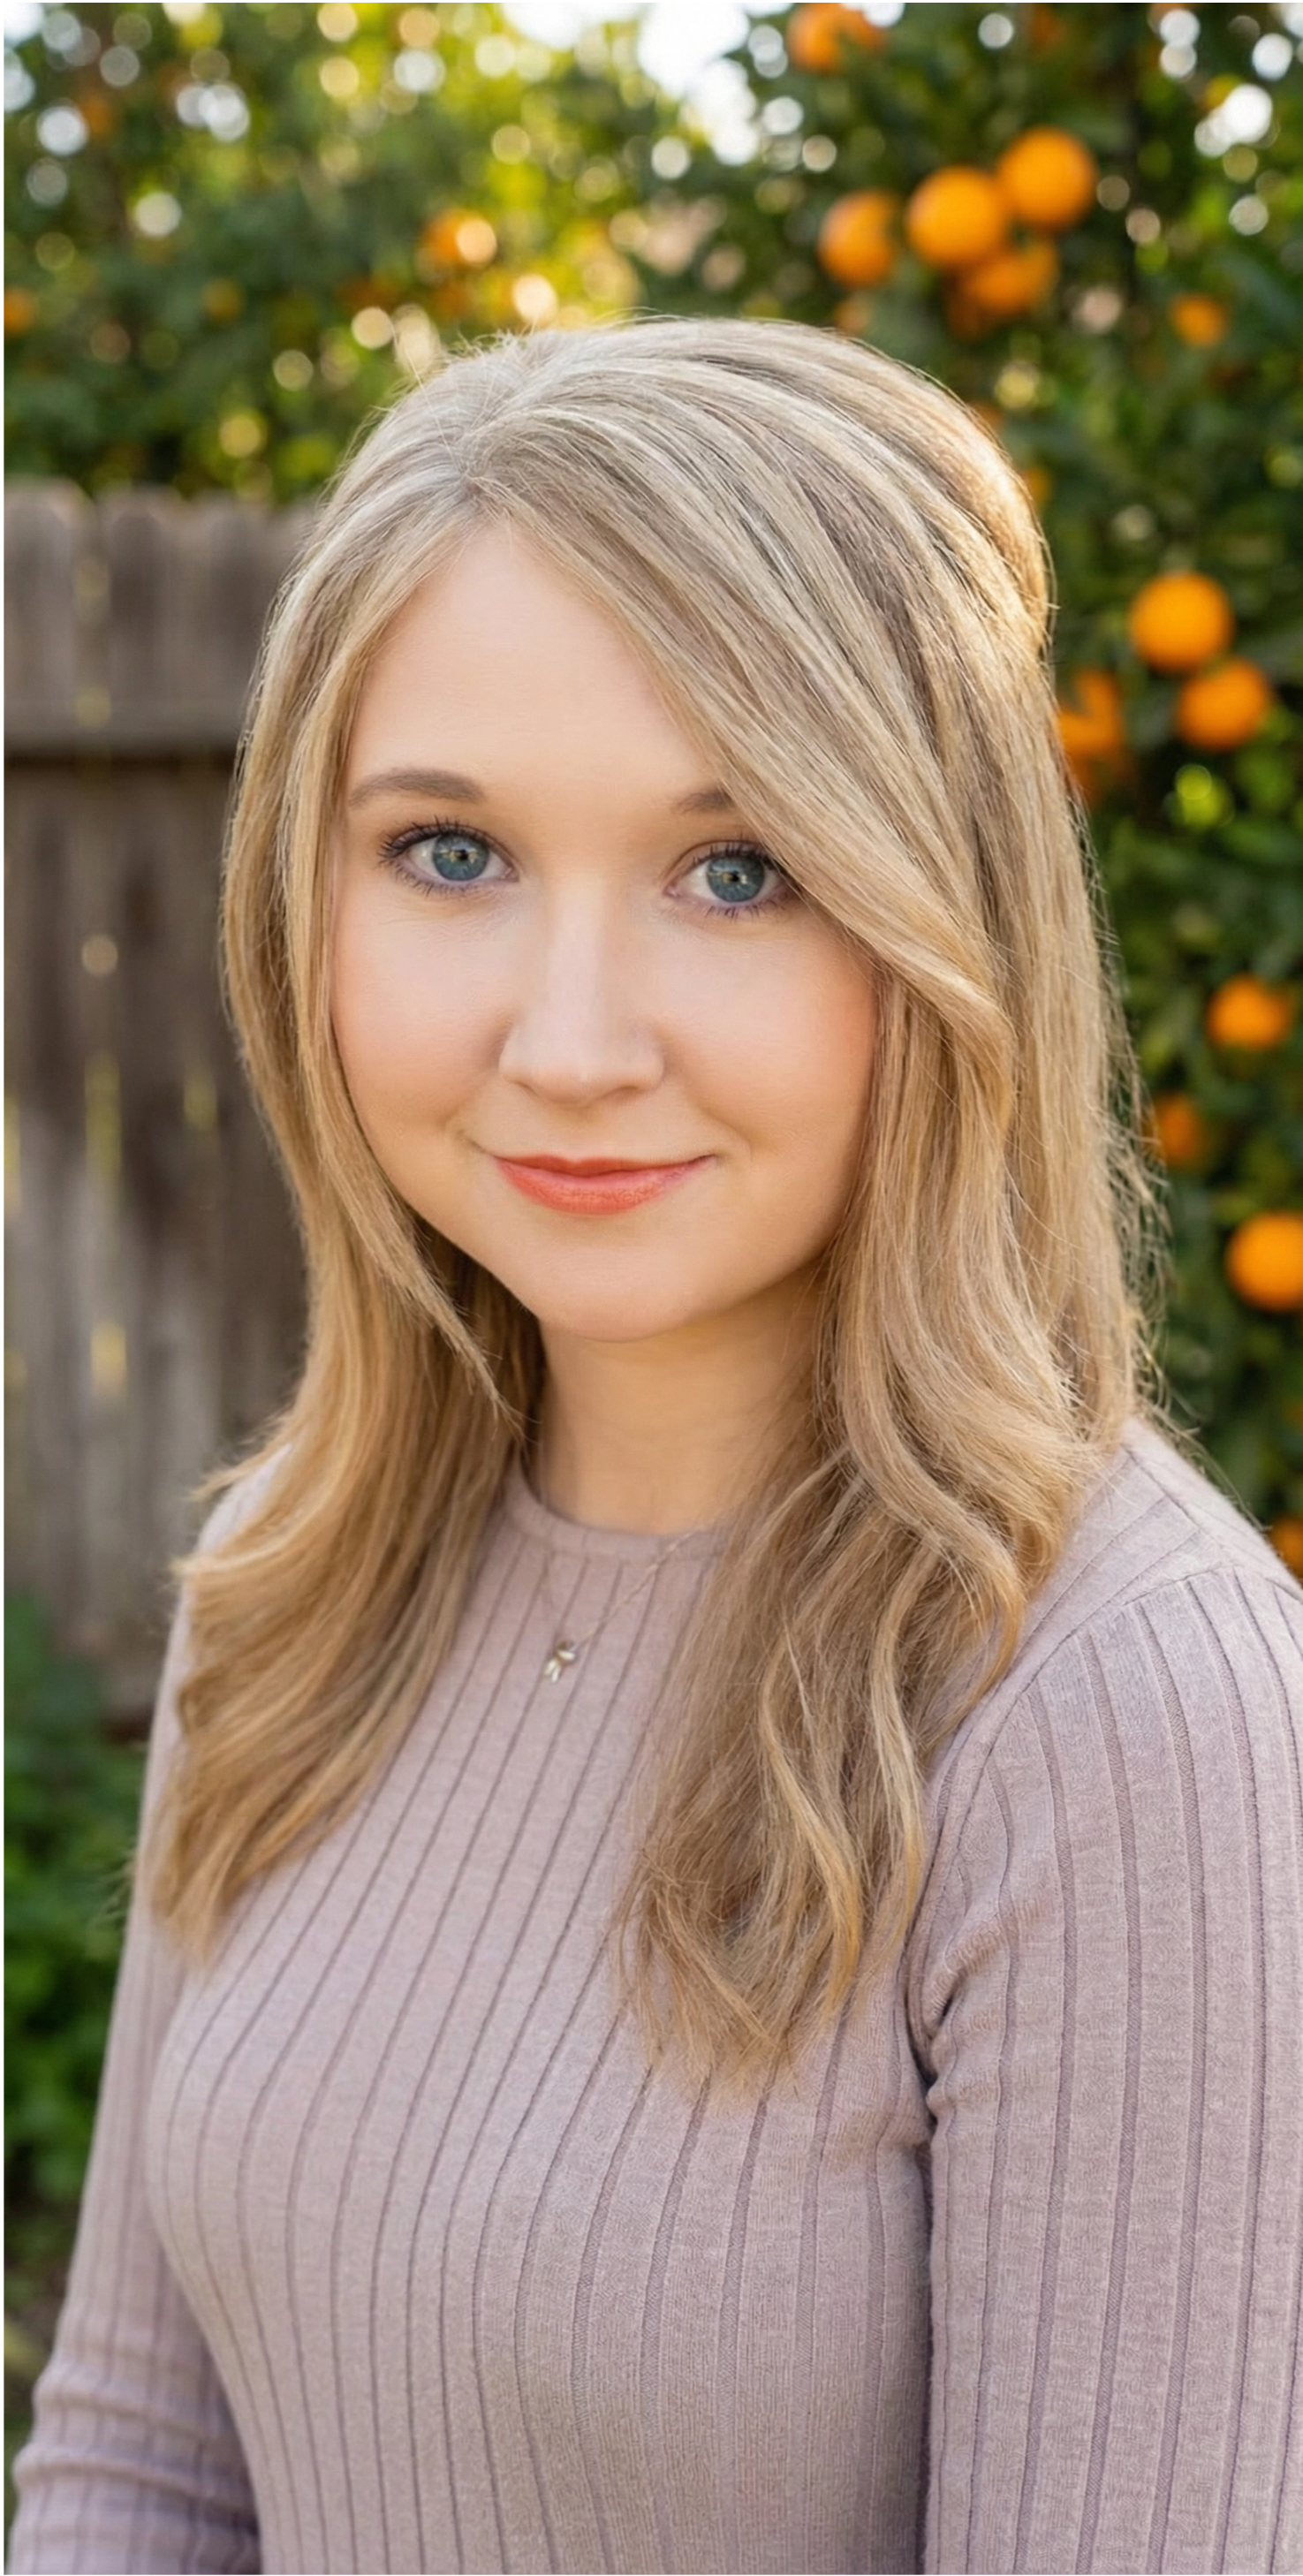
Kelly Trabert
Client Coordination + Co-Owner
Sonoma County native. Lost her family home in the 2017 Tubbs Fire and walked through a total-loss claim as the homeowner. That experience is why fire restoration sits at the center of what SRS does. Kelly is the single point of contact for adjusters, the homeowner, and the file — scheduling, photo updates, change orders, supplemental requests, the long tail of decisions that a claim depends on.
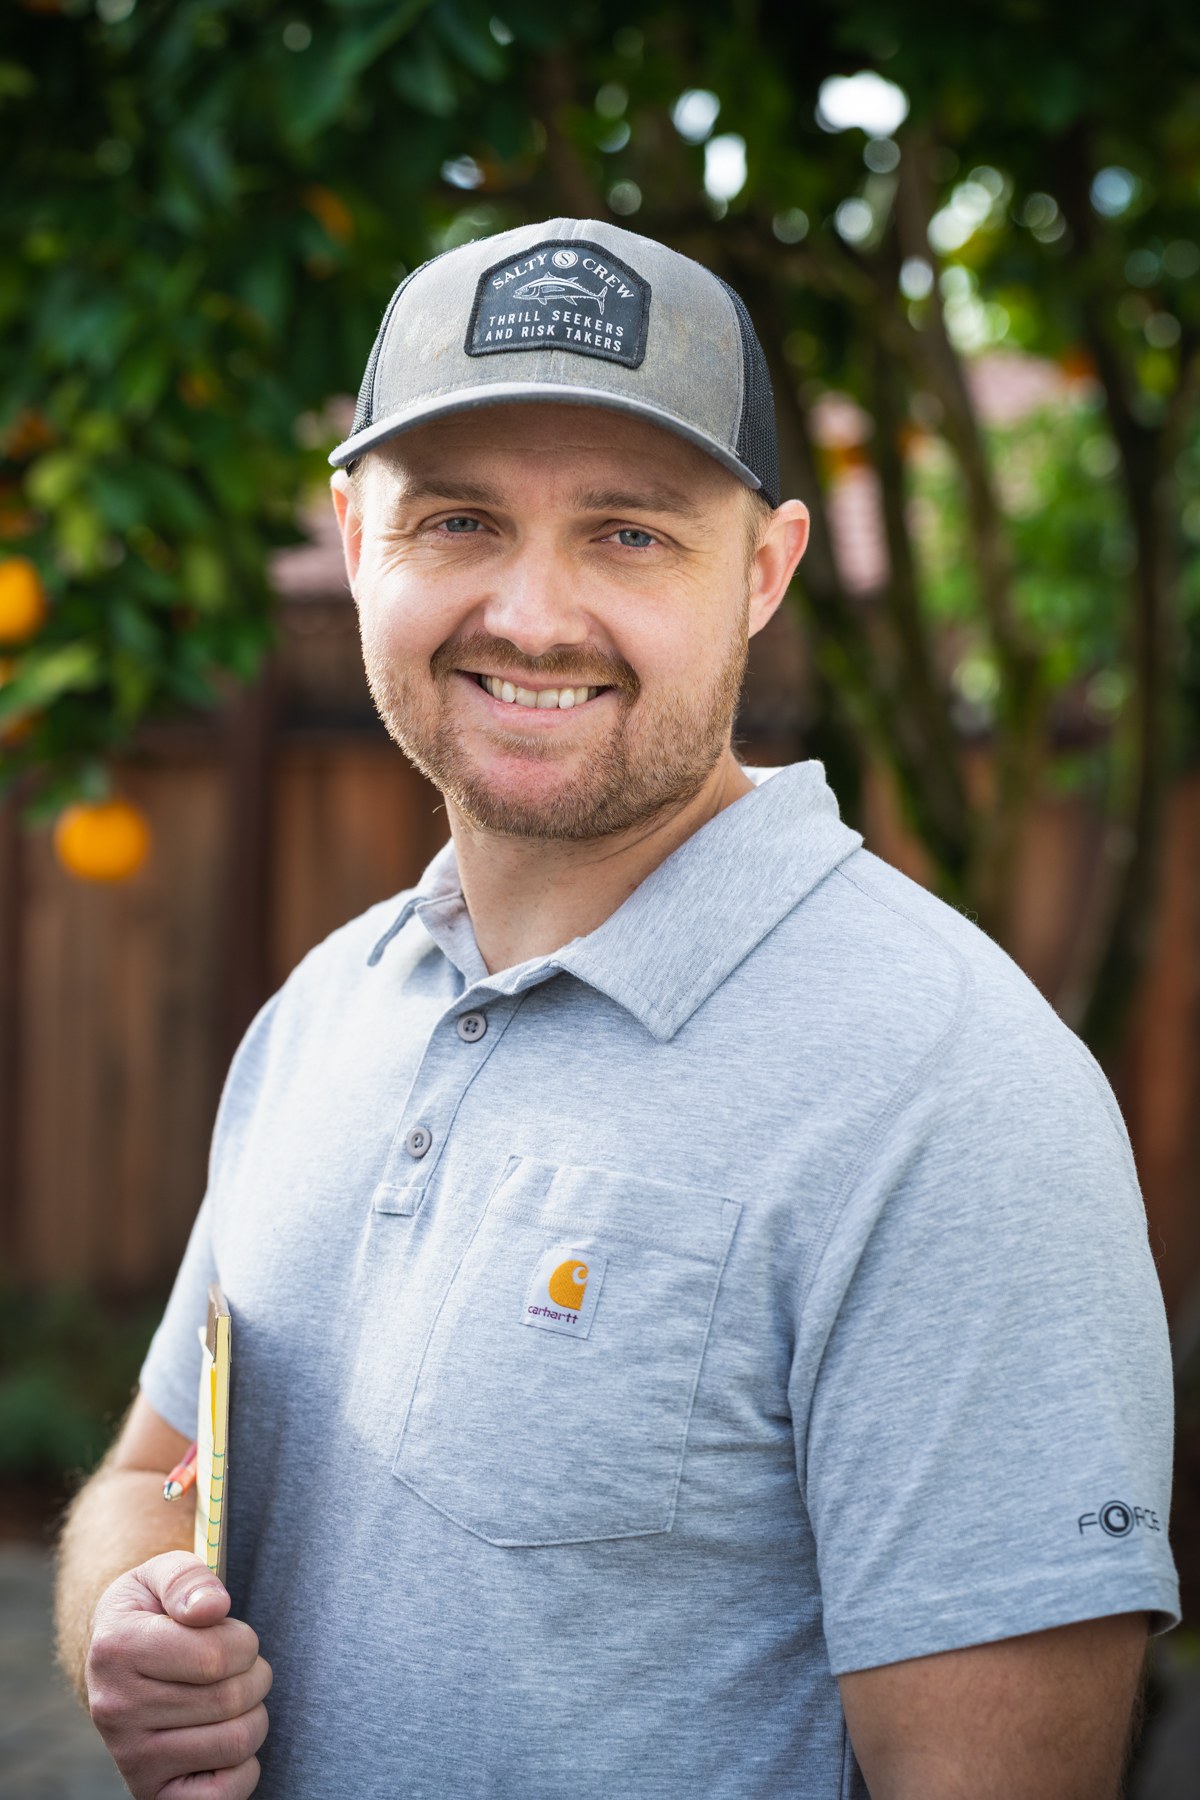
Ryan Trabert
Lead Builder + Co-Owner
Air Force veteran with a master's in construction management. Raised on his father Don's job sites — Don built custom homes for fifty years across Hawaii, California, and Idaho. Ryan is on-site every day across active projects: framing reviews, sub coordination, code-compliance verification, and the standards that show up at the final walkthrough.
Why Adjusters Work With Us
Four things that keep the file moving
Documentation That Supports the File
Every phase photographed in-house. Every change logged. Every scope item written in plain language with measurable specs. The file you build for your homeowner is supported, not undermined, by what we deliver.
Thorough Scoping
We catch what initial assessments miss. Not by padding — by knowing where claims fall short. Kelly went through her own total-loss claim after Tubbs and learned what gets overlooked. That experience now shapes every site visit we do.
Single Point of Contact
Kelly handles the adjuster relationship from intake to closeout. You get one person. One email thread. One phone number. No "that's not my department."
On-Site Every Day
Ryan (Air Force vet, master's in construction management) is on the build daily. The schedule holds because someone's watching it constantly. The homeowner isn't calling you to ask why nothing's happening this week.
Honesty Up Front
What we don't do
We'd rather tell you now than find out at the wrong moment.
Cut corners on documentation
If a phase isn't fully photographed and noted, we don't move on. Documentation is the file. The file is everything.
Push back on legitimate scope
If a scope item belongs in the claim, it goes in the claim. We don't argue with adjusters — we present what's there and let the file speak.
Disappear mid-claim
We don't subcontract the project to disappear. Kelly is the single point of contact from intake through final closeout. Same person, the entire job.
Take work outside our area
We don't take jobs in San Francisco or the East Bay. Drive time eats into the daily on-site supervision a fire rebuild requires.
Take on more than we can supervise
We run a finite number of active projects. We'd rather decline than take on a job we can't watch every day.
Ghost on warranty work
We respond to post-closeout issues within 48 hours, in person. Local. Not going anywhere.
How a Referral Works
From your introduction to the final claim closeout
You stay informed without becoming a project manager. We handle the homeowner. The file builds itself as we go.
01
Initial Site Visit
Within 48 hours of your referral, we're on-site. Walk the property with the homeowner. Document conditions. Identify safety concerns and immediate stabilization needs. You get a written summary the same day.
02
Thorough Scope Documentation
Detailed scope of work in plain language. Photos cataloged by room and condition. We catch what initial assessments often miss — code upgrades, hidden damage, restoration of finishes that were specific to the lost home.
03
Insurance Coordination + Estimate
We coordinate with you and your file. Estimate written in a format that supports the claim. If supplemental scope emerges later, we document it the same way — clear, sourced, defensible.
04
Build with Documentation
Demolition, foundation, structural, MEP, finishes — all photographed in-house at every milestone. Weekly written updates to the homeowner with you copied. Change orders priced and signed before any change touches the work.
05
Final Closeout + File Support
Walk-through with the homeowner. Punch-list resolved within 14 days. Closeout package: final photos, change-order log, lien releases, warranty docs. Everything you need to close the file cleanly.
Adjuster FAQ
Questions adjusters actually ask us
What's a typical timeline for a total-loss rebuild?
12–18 months from initial site visit to final walkthrough — including permitting, planning, and construction. Lot conditions, scope changes, and permit timelines drive variance. We give you a realistic schedule on day one.
Do you work with public adjusters and staff adjusters?
Both. The file is the file regardless of who's writing it. We don't take a side — we document what's there.
How do you handle supplemental claims?
When supplemental scope emerges (hidden damage, code upgrades, finish-level changes), we document it the same way as the initial scope: photos, written narrative, defensible cost basis. We submit through you, not around you.
Who's the day-to-day contact for the adjuster?
Kelly. One person, always. Her direct line, her email, her phone. You don't get bounced between project managers, schedulers, or office staff.
Do you coordinate ALE (Additional Living Expenses) timing?
We give the homeowner and the adjuster realistic schedule milestones, including likely move-in dates. If the schedule shifts, you hear about it the same week — not at the end of the month when ALE runs out.
How do you handle code-upgrade coverage?
We document required upgrades against the original conditions. We don't assume code upgrades are or aren't covered — we present the requirement and let you and the file resolve coverage.
What if the homeowner wants something different than what was lost?
Common in total-loss rebuilds. We work within the claim envelope and document any scope outside the claim as homeowner-paid additions. Clear separation, clear paper trail.
Where do you work geographically?
Sonoma County, Marin County, parts of Napa. We don't take fire-restoration work in SF or the East Bay — drive time degrades the daily on-site supervision a rebuild deserves.
Where We Work, What We Restore
Service area + claim-size fit
Geographic Reach
- Sonoma County: Santa Rosa, Healdsburg, Sebastopol, Sonoma, Petaluma, Windsor, Kenwood, Glen Ellen, Fountaingrove, Coffey Park
- Marin County: Tiburon, Mill Valley, Kentfield, San Anselmo, Sausalito, San Rafael
- Napa Valley: Yountville, St. Helena, Calistoga (case-by-case)
- Not currently: SF, East Bay, Peninsula, South Bay.
Claim Size + Type
- Sweet spot: $300K–$2M total-loss residential
- Largest: $5M+ luxury rebuilds
- Project types: Fire, smoke, water, structural — full restoration
- Project size: No minimum — we handle everything from small repairs to full rebuilds
50+ Years
Family Legacy
#1074033
CSLB License
Always
Fully Insured + Bonded
Certified
Veteran & Woman-Owned
Let's talk about your next file
20 minutes. No pitch. We'll learn how you work, share how we approach a claim, and figure out if there's a homeowner on your desk where we'd add real value.